Skip to content
Free Demand Writer
Menu
Free Demand Writer

Free Promissory Note / Personal Loan Demand Letter

A promissory note demand letter tells a borrower, and any guarantor, that the loan is in default and asks for payment under the note's own terms. The note usually decides most of the letter: what counts as a default, whether notice and a chance to cure are required, whether the lender can accelerate the full balance, and what interest and fees can be added.

Free Demand Writer reads the note, any guaranty or security agreement, and the payment history you upload and drafts an editable Word letter. It quotes the default and acceleration terms with page citations, lays out the payments in date order, and leaves the balance for you to confirm.

New to this kind of letter? Our guide explains what goes into a demand letter, when to send one and what happens next.

  • Free
  • No sign-up
  • Editable Word (.docx)
  • Files deleted after drafting

When to use this letter

Use this letter when a borrower has missed payments or failed to repay at maturity, and the lender wants payment before suing or enforcing security. Typical cases:

  • A business loan or seller-financed note with missed installments.
  • A personal loan between friends, family members or business partners, documented by a note, an IOU or written messages.
  • A note that matured without full repayment.
  • A default by the borrower where a personal guarantor also signed.
  • A secured loan where the lender wants payment before taking steps against the collateral.

If the loan is secured by real estate or a vehicle, foreclosure and repossession have their own notice rules that vary by state. This letter is a demand for payment; it does not replace those notices.

What to upload

Upload up to 5 PDFs, 500 pages in total. The signed note is the most important document.

The promissory note
The signed note with every page, plus any amendments, extensions or forbearance agreements.
Guaranty and security documents
A personal guaranty, security agreement, mortgage or deed of trust, if any.
Proof the money was paid out
A wire confirmation, cancelled check or bank statement showing the loan was funded, especially for informal loans.
Payment history
A ledger, amortization schedule or bank records of each payment received.
Prior notices and messages
Any notice of default, late notices, and emails or texts where the borrower acknowledged the debt or promised to pay.

What the draft includes

An editable Word letter built only from what your documents say. Missing facts become [ADD: …] placeholders, never guesses, and any law cited is marked [VERIFY].

  1. Please verify box. A short notice at the top reminding the reviewer that this is an unverified AI draft.
  2. Parties and loan details. Lender, borrower, guarantors, note date, original principal and interest rate, as the documents state them.
  3. The default. Which payment or obligation was missed, with the note's default clause quoted and cited.
  4. Notice, cure and acceleration. What the note says about notice, a cure period and accelerating the balance. Left as [VERIFY] if the note is silent or unclear.
  5. Payment history and balance. Payments received in date order, with principal, accrued interest and any fees the note allows, as a total for you to confirm.
  6. Guarantor notice. A demand addressed to each guarantor, if the documents include a guaranty.
  7. The demand. The amount and deadline are placeholders for you to set.

Before you send it

The result is an unverified AI draft for attorney review, not legal advice.

  • Recalculate interest from the note's rate and dates. Check default rate clauses and any state interest limits.
  • Confirm whether the note requires notice or a cure period before acceleration, and how notice must be delivered.
  • Check the note's notice address for the borrower and each guarantor.
  • Set the amount and deadline, and remove the Please verify box.

Common mistakes

Note defaults are usually easy to prove. The demand gets into trouble on the terms around it.

  • Accelerating without the required notice Many notes require notice of default and a chance to cure before the full balance can be called. Demanding the whole balance too early can give the borrower a defense.
  • Wrong interest math Simple versus compound interest, the default rate start date and how payments were applied all change the balance. Interest limits vary by state, and a rate above them can create exposure.
  • Forgetting the guarantor A guarantor may need its own notice under the guaranty. Send it to the address in the guaranty, not only to the borrower.
  • Thin proof on an informal loan Without a signed note, the lender needs proof that the money was a loan, not a gift. Gather the transfer records and any written acknowledgment of the debt.
  • Letting time run Filing deadlines for written and oral agreements vary by state, and a payment or acknowledgment can sometimes affect them. Check the deadline before sending.

Free promissory note / personal loan demand letter template

Prefer to write it yourself? Download a plain Word template with fields to fill in. No AI, no email needed. Sample template, not legal advice.

Questions

Is the promissory note demand letter free?

Yes. No account and no payment.

Can I use it for a personal loan with no formal note?

Yes. Upload the texts, emails and bank records that show the loan and the repayment terms. The draft uses only what they say and marks gaps with placeholders.

Will it calculate interest?

It shows the rate and dates from the note and the payments from the ledger. Treat any interest total as a starting point and recalculate it before sending.

Does it declare the loan accelerated?

Only if the note allows it, and the clause is cited. Whether to accelerate, and when, is your decision.

What happens to the documents I upload?

They are used only to draft the letter and deleted as soon as the draft is generated. The Word file is deleted after 48 hours or 3 downloads.
Fictional sample

See a sample draft

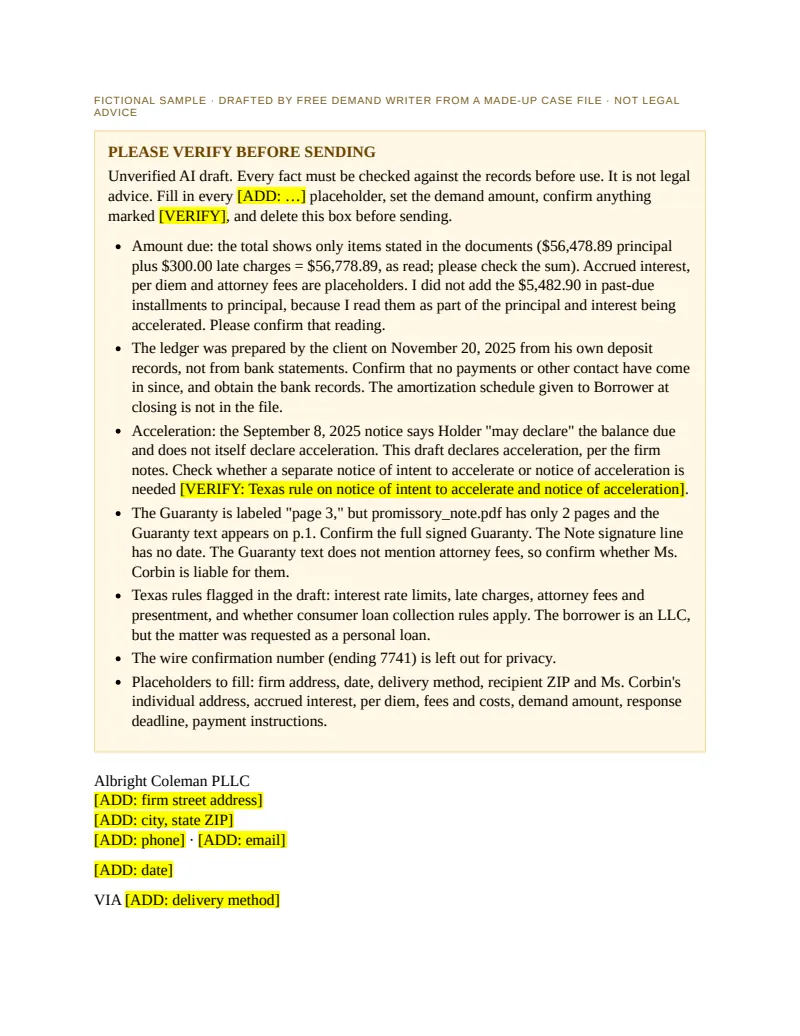
We made up a case file and ran it through Free Demand Writer, the same way your documents would be. This is the unedited draft. Everything in it is fictional: the people, the companies and the facts. A Texas investor lent a coffee shop company money under a signed note with a personal guaranty, and the borrower stopped paying after four installments.

Fictional case file: promissory_note.pdf, payment_ledger.pdf, default_notice_and_messages.pdf · State: Texas

Page 1 of a fictional sample promissory note / personal loan demand letter drafted by Free Demand Writer Download sample PDF

Fictional sample. Not legal advice. Your draft is built from your own documents.

Fictional sample · letter text

PLEASE VERIFY BEFORE SENDING

Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.

  • Amount due: the total shows only items stated in the documents ($56,478.89 principal plus $300.00 late charges = $56,778.89, as read; please check the sum). Accrued interest, per diem and attorney fees are placeholders. I did not add the $5,482.90 in past-due installments to principal, because I read them as part of the principal and interest being accelerated. Please confirm that reading.
  • The ledger was prepared by the client on November 20, 2025 from his own deposit records, not from bank statements. Confirm that no payments or other contact have come in since, and obtain the bank records. The amortization schedule given to Borrower at closing is not in the file.
  • Acceleration: the September 8, 2025 notice says Holder "may declare" the balance due and does not itself declare acceleration. This draft declares acceleration, per the firm notes. Check whether a separate notice of intent to accelerate or notice of acceleration is needed [VERIFY: Texas rule on notice of intent to accelerate and notice of acceleration].
  • The Guaranty is labeled "page 3," but promissory_note.pdf has only 2 pages and the Guaranty text appears on p.1. Confirm the full signed Guaranty. The Note signature line has no date. The Guaranty text does not mention attorney fees, so confirm whether Ms. Corbin is liable for them.
  • Texas rules flagged in the draft: interest rate limits, late charges, attorney fees and presentment, and whether consumer loan collection rules apply. The borrower is an LLC, but the matter was requested as a personal loan.
  • The wire confirmation number (ending 7741) is left out for privacy.
  • Placeholders to fill: firm address, date, delivery method, recipient ZIP and Ms. Corbin's individual address, accrued interest, per diem, fees and costs, demand amount, response deadline, payment instructions.

Albright Coleman PLLC
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]

[ADD: date]

VIA [ADD: delivery method]

Corbin Flats Coffee LLC
Attention: Shauna Corbin, Managing Member
305 Pecan Row
Alder Springs, Texas [ADD: ZIP] [default_notice_and_messages.pdf p.1]

Shauna Corbin, individually, as Guarantor
[ADD: Ms. Corbin's address]

Re: Demand for Payment and Notice of Acceleration. Promissory Note dated January 10, 2025, Principal $60,000.00. Lender: Gordon Albrecht. Borrower: Corbin Flats Coffee LLC. Guarantor: Shauna Corbin. Loan/account no. [ADD: loan or account number, if any]

Dear Ms. Corbin:

Introduction

We represent Gordon Albrecht, the Holder of the Promissory Note dated January 10, 2025 (the "Note"), signed by Corbin Flats Coffee LLC ("Borrower") through you as Managing Member [promissory_note.pdf p.1]. You also signed the Guaranty of the Note in your individual capacity on January 10, 2025 [promissory_note.pdf p.1]. This letter demands payment of the amounts due under the Note and the Guaranty. If you or Borrower are represented by counsel, please give this letter to your attorney and have him or her contact us.

The note

Mr. Albrecht wired $60,000.00 to Borrower on January 13, 2025 [promissory_note.pdf p.2]. The Note provides in relevant part:

  • Principal and interest: Borrower promised to pay $60,000.00 "with interest on the unpaid principal at 8.0% per year" (Section 1) [promissory_note.pdf p.1].
  • Payments: monthly installments of $1,216.58 beginning March 1, 2025 and on the first day of each month after that, until the Maturity Date of February 1, 2030 (Section 2) [promissory_note.pdf p.1].
  • Late charge: "Any installment not received by the 10th of the month in which it is due incurs a late charge of $60.00" (Section 3) [promissory_note.pdf p.1].
  • Default: Borrower is in default if "any installment is not paid when due" (Section 4) [promissory_note.pdf p.1].
  • Notice and acceleration: on default, Holder may send written notice of default stating a cure date. If Borrower does not pay all past due amounts by the cure date, Holder "may declare the entire unpaid principal, accrued interest and late charges immediately due" (Section 5) [promissory_note.pdf p.1].
  • Collection costs: Borrower agrees to pay Holder's "reasonable attorney fees and costs of collection" (Section 6) [promissory_note.pdf p.1].
  • Governing law: Texas (Section 7) [promissory_note.pdf p.1].
  • Security: the Note is unsecured. The only credit support is the Guaranty [payment_ledger.pdf p.1].

The Guaranty states: "The undersigned unconditionally guarantees to Holder the full and prompt payment of this Note when due, whether at maturity, by acceleration or otherwise, and agrees that Holder need not first proceed against Borrower." [promissory_note.pdf p.1]

The default

Borrower made the installments due March 1 through June 1, 2025. It paid $600.00 of the $1,216.58 installment due July 1, 2025, by check no. 1047 on July 18, 2025, and has made no payment since [payment_ledger.pdf p.1; default_notice_and_messages.pdf p.1]. No extension, forbearance or amendment of the Note has been signed [payment_ledger.pdf p.1].

Due dateAmount dueAmount paidUnpaid installmentSource
July 1, 2025$1,216.58$600.00$616.58payment_ledger.pdf p.1
August 1, 2025$1,216.58$0.00$1,216.58payment_ledger.pdf p.1
September 1, 2025$1,216.58$0.00$1,216.58payment_ledger.pdf p.1
October 1, 2025$1,216.58$0.00$1,216.58payment_ledger.pdf p.1
November 1, 2025$1,216.58$0.00$1,216.58payment_ledger.pdf p.1

The ledger states past-due installments of $5,482.90 (the July shortfall of $616.58 plus the August through November installments) as of November 20, 2025 [payment_ledger.pdf p.1].

Mr. Albrecht sent a written Notice of Default dated September 8, 2025, to Borrower, attention Ms. Corbin, with a copy to you as guarantor, by certified mail, return receipt requested, and by email. The return receipt was signed by S. Corbin on September 11, 2025 [default_notice_and_messages.pdf p.1]. The notice identified the defaulted installments due July 1, August 1 and September 1, 2025, stated a past-due amount of $3,049.74 plus late charges of $180.00, and set a cure date of October 1, 2025 [default_notice_and_messages.pdf p.1].

You acknowledged the debt in writing. On August 15, 2025 you wrote, "I know I owe you." On September 12, 2025 you wrote, "Got your letter. I am working on a refinance with my bank and will pay you everything I owe." On October 20, 2025 you wrote, "Bank said no. I'm trying to find another lender." [default_notice_and_messages.pdf p.1] Nothing was paid by the cure date, and no payments or messages have been received from Borrower or you since October 20, 2025 [default_notice_and_messages.pdf p.1; payment_ledger.pdf p.1].

Amount due

ItemAmountSource
Unpaid principal balance$56,478.89payment_ledger.pdf p.1
Late charges assessed (July through November 2025)$300.00payment_ledger.pdf p.1; promissory_note.pdf p.1 (Section 3)
Accrued unpaid interest at 8.0% per year[ADD: accrued interest through payment date]promissory_note.pdf p.1 (Section 1)
Attorney fees and costs of collection[ADD: attorney fees and costs to date]promissory_note.pdf p.1 (Section 6)
Total (as read from the bills), stated items only (principal and late charges)$56,778.89

Interest continues to accrue at the Note rate of 8.0% per year until payment [ADD: per diem interest amount]. The ledger does not include interest accrued after November 1, 2025 [payment_ledger.pdf p.1]. Payments were applied first to accrued interest and then to principal [payment_ledger.pdf p.1].

Notice and acceleration

Section 5 of the Note allows Holder, after written notice of default and the passing of the cure date without payment of all past due amounts, to declare the entire unpaid principal, accrued interest and late charges immediately due [promissory_note.pdf p.1]. Written notice of default was sent on September 8, 2025 and received on September 11, 2025, with a cure date of October 1, 2025 [default_notice_and_messages.pdf p.1]. The past-due amounts were not paid by that date [firm notes; default_notice_and_messages.pdf p.1].

Accordingly, Mr. Albrecht declares the entire unpaid principal, accrued interest and late charges under the Note immediately due and payable. Under the Guaranty, you are liable for that full amount, "whether at maturity, by acceleration or otherwise," and Mr. Albrecht need not first proceed against Borrower [promissory_note.pdf p.1]. [VERIFY: Texas rule on notice of intent to accelerate and notice of acceleration]

Demand

We demand that Borrower and you, jointly and severally as Borrower and Guarantor, pay [ADD: demand amount] by [ADD: response deadline]. Payment must be made by [ADD: payment instructions].

If payment is not received by that date, we are authorized to take the steps we consider appropriate to collect the debt, including recovery of the attorney fees and costs of collection provided in Section 6 of the Note [promissory_note.pdf p.1]. [ADD: authorization to file suit, if confirmed by client] Mr. Albrecht reserves all rights and remedies under the Note, the Guaranty and applicable law. Nothing in this letter waives any right or remedy, and no prior forbearance or communication changes the terms of the Note.

State rules

The Note provides that Texas law governs [promissory_note.pdf p.1]. This letter is intended to follow the notice, cure and acceleration terms of the Note. The following Texas points require attorney confirmation before this letter is sent:

  • [VERIFY: Texas rule on interest rate limits] as applied to the 8.0% rate in the Note.
  • [VERIFY: Texas rule on enforceability of late charges] as applied to the $60.00 charge in Section 3.
  • [VERIFY: Texas rule on recovery of attorney fees, including any presentment requirement].
  • [VERIFY: whether Texas consumer loan collection rules apply] to this loan and to the Guaranty.

Sincerely,

Natalie J. Coleman
Albright Coleman PLLC