Skip to content
Free Demand Writer
Menu
Free Demand Writer

Free Accounting / Professional Malpractice Demand Letter

An accounting or professional malpractice demand letter tells a CPA, architect, engineer or consultant that their work fell below the standard of their profession and cost your client money. It puts the professional and their liability carrier on notice and opens settlement talks before suit.

Free Demand Writer reads the engagement letter, the work product and the loss records you upload and drafts an editable Word letter. It sets out the scope of the engagement, what went wrong in date order and the documented losses, cited to each file and page, and leaves the standard of care opinion, the demand and the deadline for your attorney.

New to this kind of letter? Our guide explains what goes into a demand letter, when to send one and what happens next.

  • Free
  • No sign-up
  • Editable Word (.docx)
  • Files deleted after drafting

When to use this letter

Use this letter when a hired professional made an error or gave advice that a careful member of the profession would not have, and the client can show a loss. Typical cases:

  • A CPA prepared a return with errors that led to penalties, interest or a lost deduction.
  • An accountant missed a filing or election deadline, or failed to catch problems in an audit or review.
  • An architect's or engineer's plans had design errors that caused rework, delays or code violations.
  • A consultant's advice or report was wrong in a way that caused a failed project or financial loss.
  • A bookkeeper or payroll provider made errors that triggered tax notices or fines.

Some states require a certificate of merit or an expert affidavit before suing an architect or engineer, and other professions may have similar rules. Filing deadlines also vary by state and by profession. The draft marks these points [VERIFY] for your attorney to check.

What to upload

Upload up to 5 PDFs, 500 pages in total. The engagement letter and the work product at issue matter most.

The engagement letter or contract
The signed agreement that sets the scope of services, fees, any limitation of liability and dispute resolution terms.
The work product
The tax return, audit report, financial statements, drawings, specifications or written advice at issue.
Notices and findings
IRS or state tax notices, building department corrections, inspection reports or a replacement professional's findings.
Correspondence
Emails and letters with the professional about the work, the problem and any attempt to fix it.
Loss documents
Penalty and interest statements, invoices for corrective work, fees paid and proof of lost value.

What the draft includes

An editable Word letter built only from what your documents say. Missing facts become [ADD: …] placeholders, never guesses, and any law cited is marked [VERIFY].

  1. Please verify box. A short notice at the top reminding the reviewer that this is an unverified AI draft.
  2. The engagement. Parties, date, scope and key terms, quoted or summarized with the page they come from.
  3. Timeline of the work and the errors. What the professional did and what went wrong, in date order, drawn only from the documents.
  4. Standard of care. Built from your expert's opinion where uploaded. Without one, a placeholder for the attorney, never a guess.
  5. Damages table. Penalties, corrective costs, fees and other losses, each tied to a source document.
  6. Preservation request. A request that the professional keep the engagement file and work papers.
  7. The demand. The amount and response deadline are always placeholders for you to set.

Before you send it

The result is an unverified AI draft for attorney review, not legal advice.

  • Read the engagement scope and any limitation of liability clause against the claim.
  • Check whether your state requires a certificate of merit or expert support for this profession.
  • Have a qualified expert confirm the standard of care and causation statements.
  • Match every date and amount to the cited page.
  • Set the amount and deadline, and remove the Please verify box.

Common mistakes

Professional liability carriers review these letters with their own experts. These are the gaps they look for.

  • Claiming outside the scope A professional is usually measured against what they agreed to do. If the task was not in the engagement, the claim gets harder. Quote the scope.
  • Missing the limitation of liability clause Many engagement letters cap damages or require arbitration. Find these terms before you set the demand.
  • Counting losses the client owed anyway Tax that was always due is often not a recoverable loss, while penalties and interest may be. Separate the two in the damages table.
  • No expert support A bad result is not proof of negligence. The letter is stronger when an expert in the same field has reviewed the work.

Free accounting / professional malpractice demand letter template

Prefer to write it yourself? Download a plain Word template with fields to fill in. No AI, no email needed. Sample template, not legal advice.

Questions

Is the accounting and professional malpractice demand letter free?

Yes. No account and no payment.

Which professionals does it cover?

Accountants, CPAs, bookkeepers, architects, engineers and consultants. For a claim against a lawyer, use the legal malpractice letter.

Does the draft give a standard of care opinion?

No. It uses your expert's written opinion if you upload one, and otherwise leaves a placeholder.

Does it handle certificate of merit rules?

It does not decide which rules apply. Some states require one for architects and engineers, and the draft marks this [VERIFY] for your attorney.

What happens to the documents I upload?

They are deleted as soon as the draft is generated. The Word file is deleted after 48 hours or 3 downloads.
Fictional sample

See a sample draft

We made up a case file and ran it through Free Demand Writer, the same way your documents would be. This is the unedited draft. Everything in it is fictional: the people, the companies and the facts. A Wisconsin machine shop was hit with late-filing penalties after its CPA firm, which had all the records months early, never filed the company's 2024 S corporation return or an extension.

Fictional case file: cpa_engagement_letter.pdf, tax_penalty_notices.pdf, emails_and_successor_cpa.pdf · State: Wisconsin

Page 1 of a fictional sample accounting / professional malpractice demand letter drafted by Free Demand Writer Download sample PDF

Fictional sample. Not legal advice. Your draft is built from your own documents.

Fictional sample · letter text

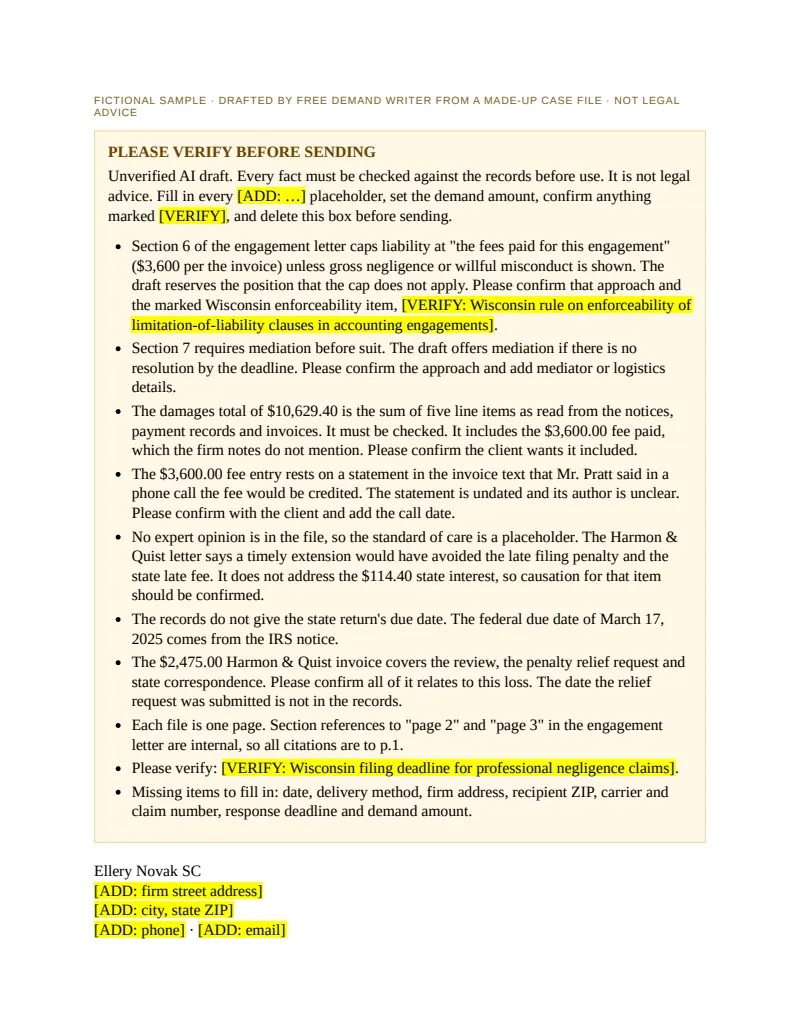
PLEASE VERIFY BEFORE SENDING

Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.

  • Section 6 of the engagement letter caps liability at "the fees paid for this engagement" ($3,600 per the invoice) unless gross negligence or willful misconduct is shown. The draft reserves the position that the cap does not apply. Please confirm that approach and the marked Wisconsin enforceability item, [VERIFY: Wisconsin rule on enforceability of limitation-of-liability clauses in accounting engagements].
  • Section 7 requires mediation before suit. The draft offers mediation if there is no resolution by the deadline. Please confirm the approach and add mediator or logistics details.
  • The damages total of $10,629.40 is the sum of five line items as read from the notices, payment records and invoices. It must be checked. It includes the $3,600.00 fee paid, which the firm notes do not mention. Please confirm the client wants it included.
  • The $3,600.00 fee entry rests on a statement in the invoice text that Mr. Pratt said in a phone call the fee would be credited. The statement is undated and its author is unclear. Please confirm with the client and add the call date.
  • No expert opinion is in the file, so the standard of care is a placeholder. The Harmon & Quist letter says a timely extension would have avoided the late filing penalty and the state late fee. It does not address the $114.40 state interest, so causation for that item should be confirmed.
  • The records do not give the state return's due date. The federal due date of March 17, 2025 comes from the IRS notice.
  • The $2,475.00 Harmon & Quist invoice covers the review, the penalty relief request and state correspondence. Please confirm all of it relates to this loss. The date the relief request was submitted is not in the records.
  • Each file is one page. Section references to "page 2" and "page 3" in the engagement letter are internal, so all citations are to p.1.
  • Please verify: [VERIFY: Wisconsin filing deadline for professional negligence claims].
  • Missing items to fill in: date, delivery method, firm address, recipient ZIP, carrier and claim number, response deadline and demand amount.

Ellery Novak SC
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]

[ADD: date]

VIA [ADD: delivery method]

Douglas Pratt, CPA, Managing Partner
Pratt Lindgren CPAs LLP
740 Lakeshore Commons Drive
Harlow Bay, Wisconsin [ADD: ZIP]

Re: Vossberg Precision Machining Inc. – Failure to File 2024 Returns or Extension by the March 17, 2025 Deadline; Claim No. [ADD: carrier claim number, if any]; Date of loss: [ADD: date of loss]

Dear Mr. Pratt:

Introduction

We represent Vossberg Precision Machining Inc. ("Vossberg") regarding the services Pratt Lindgren CPAs LLP ("Pratt Lindgren") provided under the 2024 Tax Engagement [firm notes]. Please direct all further communication about this matter to our office. We ask that you immediately notify your firm's professional liability carrier of this claim and forward this letter to it.

The engagement

By letter dated January 6, 2025, which Karl Vossberg accepted on January 9, 2025, Pratt Lindgren agreed to prepare and electronically file Vossberg's 2024 federal S corporation income tax return, the related state franchise and income tax return, and the shareholder information statements for its three shareholders [cpa_engagement_letter.pdf p.1]. Section 1 also provides: "If any return cannot be completed by its original due date, we will file an extension request on your behalf by that date." [cpa_engagement_letter.pdf p.1, Section 1]. The fee was $3,600, billed on completion [cpa_engagement_letter.pdf p.1, Section 3].

Section 2 asked Vossberg to provide its year-end trial balance, bank statements, payroll reports and fixed asset records by February 14, 2025 [cpa_engagement_letter.pdf p.1, Section 2]. Vossberg uploaded those materials to your portal on January 31, 2025, and your staff accountant, Megan Holt, confirmed receipt on February 3, 2025 [cpa_engagement_letter.pdf p.1].

The engagement letter contains a limitation-of-liability clause (Section 6) and a mediation clause (Section 7) [cpa_engagement_letter.pdf p.1]. We address both in the Demand section below.

The services and the errors

The sequence of events, as shown in the records, is as follows:

  • On March 4, 2025, Mr. Vossberg asked Ms. Holt whether the 2024 return was on track for the March deadline [emails_and_successor_cpa.pdf p.1].
  • On March 5, 2025, Ms. Holt replied: "we have everything we need. Doug is reviewing it and it will be filed on time or extended." [emails_and_successor_cpa.pdf p.1].
  • The federal return was due March 17, 2025. The IRS has no record of an extension request [tax_penalty_notices.pdf p.1]. The state return's due date was [ADD: state return due date].
  • On May 22, 2025, Mr. Vossberg wrote to you that the company's bank had asked for a copy of the filed 2024 return and that he could not find a confirmation. He asked whether it was filed or extended [emails_and_successor_cpa.pdf p.1].
  • On May 29, 2025, you replied: "I apologize. Megan left the firm in March and your return was not picked up by anyone. No extension was filed." [emails_and_successor_cpa.pdf p.1].
  • On June 30, 2025, you wrote that the federal and state returns were filed that day, that Vossberg might receive penalty notices, and that Pratt Lindgren "will not charge for the preparation." [emails_and_successor_cpa.pdf p.1]. The IRS and the state Department of Revenue both record receipt of the returns on June 30, 2025 [tax_penalty_notices.pdf p.1].

The IRS then assessed a late filing penalty of $3,940.00 (notice dated July 21, 2025), and the state assessed a late filing fee of $500.00 and late payment interest of $114.40 (notice dated August 8, 2025) [tax_penalty_notices.pdf p.1]. Vossberg paid both [tax_penalty_notices.pdf p.1]. Its request to the IRS for penalty relief was denied on November 4, 2025, leaving the $3,940.00 penalty in place [tax_penalty_notices.pdf p.1].

Vossberg's successor accountants, Harmon & Quist CPAs, reviewed the file. They reported that Vossberg provided its records to Pratt Lindgren on January 31, 2025, that Pratt Lindgren filed neither the return nor an extension by March 17, 2025, and that "[a] timely extension request would have avoided the late filing penalty and the state late fee." [emails_and_successor_cpa.pdf p.1].

Your firm undertook in writing to file an extension if the returns could not be completed by the due date, and then assured our client in writing that the return would be filed or extended. By your own account, no one at your firm acted on the file. What a careful accounting firm would have done in these circumstances is [ADD: standard of care, per expert].

Damages

Vossberg has incurred the following documented losses:

ItemDateAmountSource
IRS late filing penalty (paid)Paid August 6, 2025$3,940.00tax_penalty_notices.pdf p.1
State late filing fee (paid)Paid August 20, 2025$500.00tax_penalty_notices.pdf p.1
State late payment interest (paid with the late filing fee; $614.40 combined)Paid August 20, 2025$114.40tax_penalty_notices.pdf p.1
Harmon & Quist CPAs, Invoice HQ-2291 (review of late filing, penalty relief request, state correspondence)Invoiced November 20, 2025; paid December 1, 2025$2,475.00emails_and_successor_cpa.pdf p.1
Pratt Lindgren fee for 2024 returns, paid despite your statement that the preparation would not be chargedInvoiced July 2, 2025; paid July 15, 2025$3,600.00emails_and_successor_cpa.pdf p.1

Total (as read from the bills): $10,629.40

Regarding the last item, Vossberg paid your July 2, 2025 invoice after Mr. Pratt said in a phone call on [ADD: date of phone call] that the fee would be credited later. No credit has been issued [emails_and_successor_cpa.pdf p.1]. Vossberg's other losses, if any, are [ADD: any additional documented losses]. We reserve the right to supplement this list.

Demand

We demand payment of [ADD: demand amount] by [ADD: response deadline].

We do not accept that Section 6 of the engagement letter limits Vossberg's recovery in these circumstances, and we reserve the position that its exception for gross negligence applies [VERIFY: Wisconsin rule on enforceability of limitation-of-liability clauses in accounting engagements]. As to Section 7, if this matter is not resolved by the deadline above, Vossberg is prepared to proceed to mediation as that section provides. Please let us know by the same date whether you will agree to mediate and propose [ADD: mediator or mediation provider and proposed dates]. Vossberg reserves the right to take further action, including filing suit if mediation does not resolve the matter. Vossberg also reserves its position on the applicable time limits [VERIFY: Wisconsin filing deadline for professional negligence claims].

Please preserve all documents and electronic data relating to Vossberg and this engagement. This includes the engagement file, work papers, portal upload and access records, emails, calendar and deadline-tracking entries, staffing and assignment records for the 2024 return, and the records of the June 30, 2025 filings. Destroying or altering any of these materials could prejudice your position.

Vossberg reserves all rights and remedies. Please have your carrier contact me directly.

Sincerely,

Samuel J. Ellery
Ellery Novak SC