When to use this letter
Use this letter once the vehicle has been repaired and you have an independent appraisal of its lost value. Typical cases:
- A newer or low-mileage vehicle was repaired after a crash caused by another driver.
- The repairs involved frame, structural or airbag damage that will show on vehicle history reports.
- The insurer paid for repairs but refused or ignored a request for diminished value.
- A leased or financed vehicle will be turned in or traded with an accident on its record.
- A dealer trade-in offer dropped after the crash, and the owner has it in writing.
Whether diminished value can be recovered, how it is measured, and whether it can be claimed under the owner's own policy all vary by state. The draft marks these points [VERIFY]. If the main claim is the repair cost or loss of use, the property damage letter may fit better.
What to upload
Upload up to 5 PDFs, 500 pages in total. A written appraisal is the most important document.
- Diminished value appraisal
- The appraiser's report with the pre-loss value, the post-repair value and the method used.
- Repair estimate and final invoice
- The body shop's estimate, supplements and final invoice, showing the parts and labor.
- Crash report
- The police report or claim file notes showing how the crash happened and who was at fault.
- Photos
- Damage photos before repair, saved as PDF, especially of frame or structural damage.
- Insurer correspondence
- Liability acceptance, repair payment letters and any denial of the diminished value request.
What the draft includes
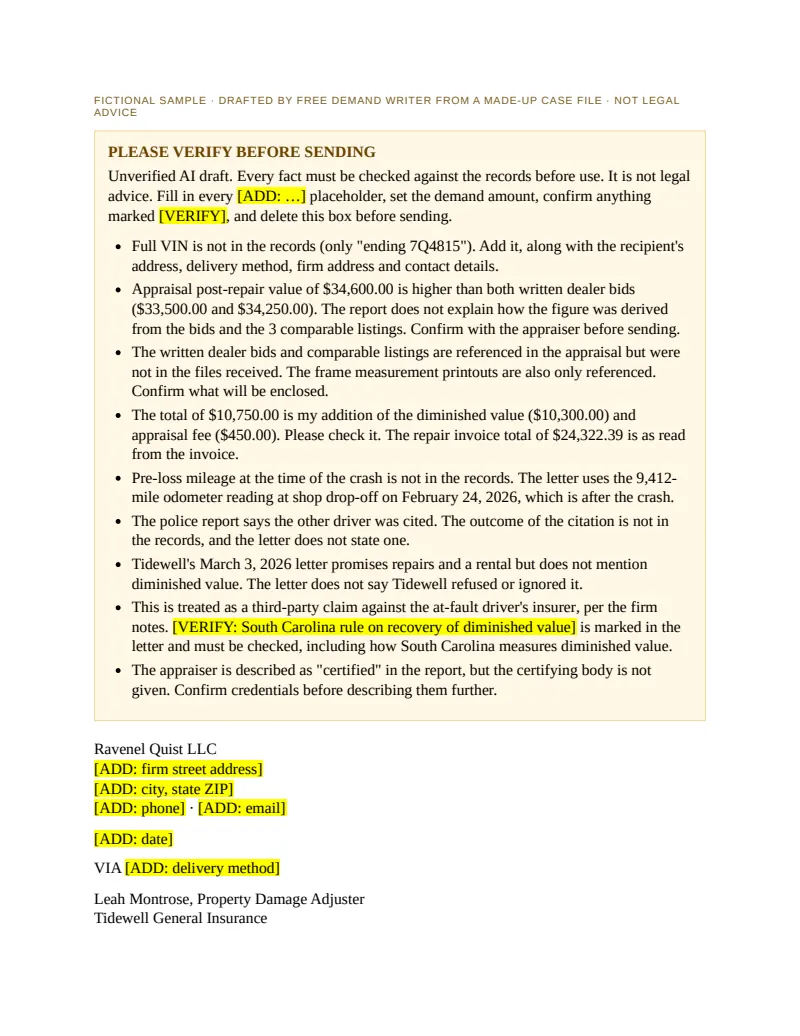
An editable Word letter built only from what your documents say. Missing facts become [ADD: …] placeholders, never guesses, and any law cited is marked [VERIFY].
- Please verify box. A short list at the top of the specific items your reviewer must check in this unverified AI draft.
- Liability summary. How the crash happened and why the insured is at fault, cited to the report.
- Vehicle and repair history. Year, make, model, mileage, the damage and the repairs, taken from the estimates and invoices.
- Diminished value table. Pre-loss value, post-repair value, diminished value and appraisal fee as read from the documents.
- State rule flags. Recovery and measurement of diminished value marked [VERIFY] for the governing state.
- The demand. The amount and response deadline are always placeholders for your attorney to set.
Before you send it
The result is an unverified AI draft for attorney review, not legal advice.
- Confirm the governing state allows a diminished value claim against this insurer.
- Check that the appraisal values and method match the figures in the draft.
- Match every date and amount to the page cited in brackets.
- Set the demand amount and deadline, and remove the Please verify box.
Common mistakes
Insurers push back hard on diminished value claims. These are the gaps they look for.
- No independent appraisal A number based on an online calculator or a guess is easy to reject. Get a written appraisal from a qualified appraiser that explains its method.
- Claiming before repairs are done The post-repair value depends on the finished repair. Wait for the final invoice and any supplements.
- Ignoring the formula the insurer uses Some insurers apply their own formula that produces low numbers. Be ready to explain why your appraisal is more reliable, without relying on rules that do not apply in your state.
- Signing a broad release A property damage release for the repair payment may cover diminished value too. Read it before your client signs.
Free diminished value auto claim demand letter template
Prefer to write it yourself? Download a plain Word template with fields to fill in. No AI, no email needed. Sample template, not legal advice.
Questions
Is the diminished value auto claim demand letter free?
Yes. No account and no payment.
Will the draft calculate the diminished value?
No. It uses only the values in the appraisal or other documents you upload. If there is no appraisal, the values are left as placeholders.
Can my client claim diminished value from their own insurer?
It depends on the policy and the state. The draft marks this point [VERIFY] so your attorney can check it.
Does it include repair costs too?
It describes the repairs to support the claim. If the repair bill is still unpaid, the property damage letter is usually the better fit.
What happens to the documents I upload?
They are deleted as soon as the draft is generated. The Word file is deleted after 48 hours or 3 downloads.