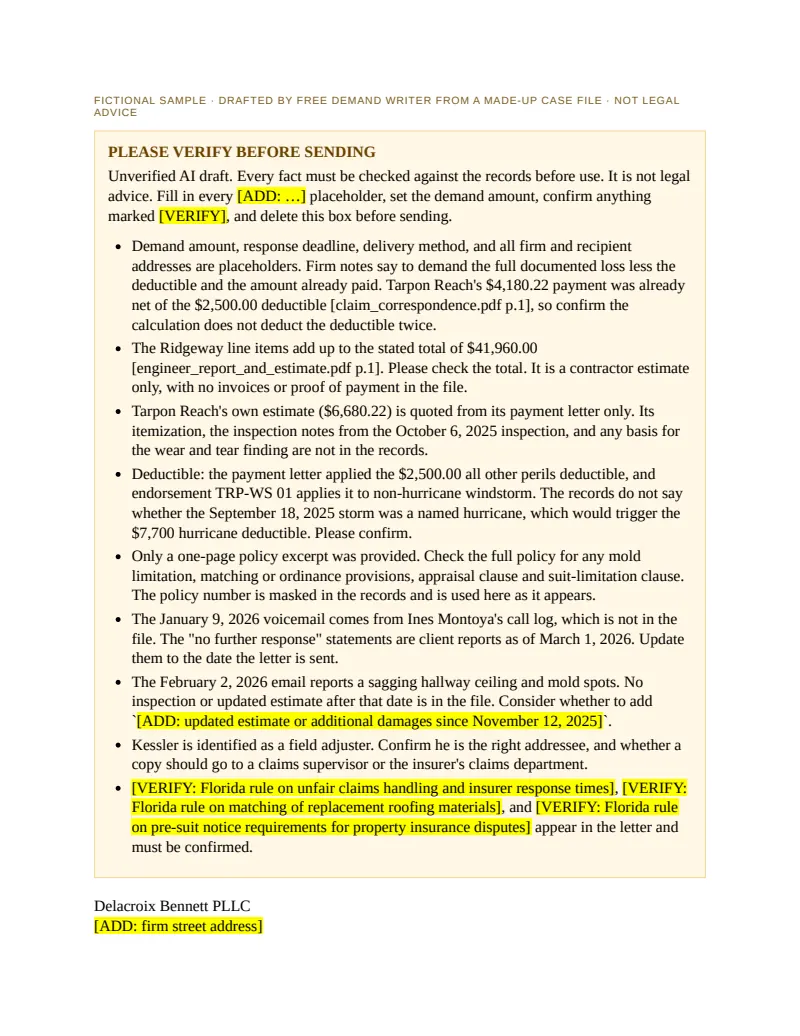
PLEASE VERIFY BEFORE SENDING
Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.
- Demand amount, response deadline, delivery method, and all firm and recipient addresses are placeholders. Firm notes say to demand the full documented loss less the deductible and the amount already paid. Tarpon Reach's $4,180.22 payment was already net of the $2,500.00 deductible [claim_correspondence.pdf p.1], so confirm the calculation does not deduct the deductible twice.
- The Ridgeway line items add up to the stated total of $41,960.00 [engineer_report_and_estimate.pdf p.1]. Please check the total. It is a contractor estimate only, with no invoices or proof of payment in the file.
- Tarpon Reach's own estimate ($6,680.22) is quoted from its payment letter only. Its itemization, the inspection notes from the October 6, 2025 inspection, and any basis for the wear and tear finding are not in the records.
- Deductible: the payment letter applied the $2,500.00 all other perils deductible, and endorsement TRP-WS 01 applies it to non-hurricane windstorm. The records do not say whether the September 18, 2025 storm was a named hurricane, which would trigger the $7,700 hurricane deductible. Please confirm.
- Only a one-page policy excerpt was provided. Check the full policy for any mold limitation, matching or ordinance provisions, appraisal clause and suit-limitation clause. The policy number is masked in the records and is used here as it appears.
- The January 9, 2026 voicemail comes from Ines Montoya's call log, which is not in the file. The "no further response" statements are client reports as of March 1, 2026. Update them to the date the letter is sent.
- The February 2, 2026 email reports a sagging hallway ceiling and mold spots. No inspection or updated estimate after that date is in the file. Consider whether to add `[ADD: updated estimate or additional damages since November 12, 2025]`.
- Kessler is identified as a field adjuster. Confirm he is the right addressee, and whether a copy should go to a claims supervisor or the insurer's claims department.
- [VERIFY: Florida rule on unfair claims handling and insurer response times], [VERIFY: Florida rule on matching of replacement roofing materials], and [VERIFY: Florida rule on pre-suit notice requirements for property insurance disputes] appear in the letter and must be confirmed.
Delacroix Bennett PLLC
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]
[ADD: date]
VIA [ADD: delivery method]
Brian Kessler, Adjuster
Tarpon Reach Property and Casualty Insurance Company
[ADD: street address]
[ADD: city, state ZIP]
Re: Demand for payment of homeowners claim. Insureds: Rafael Montoya and Ines Montoya. Claim No. TRP-25-118204. Policy No. TRP-HO-xxxx-4471. Date of loss: September 18, 2025. Property: 3127 Seabrook Lane, Palm Haven, Florida
Dear Brian Kessler:
Introduction
This firm represents Rafael Montoya and Ines Montoya in connection with claim TRP-25-118204 under the homeowners policy issued to them by Tarpon Reach Property and Casualty Insurance Company ("Tarpon Reach") [policy_declarations.pdf p.1]. Please direct all further communication about this claim to our office.
Tarpon Reach has paid only part of the loss, attributing the remainder of the roof damage to wear and tear. Our clients disagreed in writing on November 14, 2025, and sent supporting documents. We have found no substantive response in the claim file. We write to request payment of the full documented loss, less the applicable deductible and the amount already paid.
Policy and coverage
Tarpon Reach issued Homeowners Policy No. TRP-HO-xxxx-4471 to Rafael Montoya and Ines Montoya for the residence at 3127 Seabrook Lane, Palm Haven, Florida. The policy period is February 1, 2025 to February 1, 2026 [policy_declarations.pdf p.1]. The date of loss, September 18, 2025, falls within that period [claim_correspondence.pdf p.1]. The declarations show the following [policy_declarations.pdf p.1]:
- Coverage A, Dwelling: $385,000
- Coverage B, Other Structures: $38,500
- Coverage C, Personal Property: $192,500
- Coverage D, Loss of Use: $77,000
- All other perils deductible: $2,500
- Hurricane deductible: $7,700
The policy states: "We insure against direct physical loss to property described in Coverages A and B, unless the loss is excluded" (Section I, Perils Insured Against, page 9) [policy_declarations.pdf p.1]. Tarpon Reach relies on the exclusion for "loss caused by wear and tear, marring, deterioration, or mechanical breakdown" (Section I, Exclusions, page 11) [policy_declarations.pdf p.1]; [claim_correspondence.pdf p.1]. Endorsement TRP-WS 01 provides that windstorm events that are not a named hurricane are subject to the all other perils deductible [policy_declarations.pdf p.1]. Tarpon Reach applied that deductible, in the amount of $2,500.00 [claim_correspondence.pdf p.1].
Under Your Duties After Loss (Section I, Conditions, page 14), the policy requires prompt notice, protection of the property from further damage, and showing the damaged property and providing requested records [policy_declarations.pdf p.1]. Our clients did each of these. They reported the loss by email on September 19, 2025, the day after the storm, and reported that they had placed a tarp on the roof [claim_correspondence.pdf p.1]. Tarpon Reach's adjuster inspected the property on October 6, 2025 [claim_correspondence.pdf p.1].
The claim
Our clients reported that the windstorm tore shingles off the south slope and that water entered the master bedroom and hallway ceilings [claim_correspondence.pdf p.1].
Tarpon Reach's October 28, 2025 letter estimated the covered loss at $6,680.22. It subtracted the $2,500.00 deductible and enclosed a check for $4,180.22. The letter stated that "[d]amage to the remaining roof covering is due to wear and tear and deterioration and is excluded" [claim_correspondence.pdf p.1].
Our clients obtained an engineering evaluation. Thomas Ngata, PE, of Shellbank Structural Engineering, Inc. inspected the property on November 7, 2025 and issued a report dated November 10, 2025. He found that [engineer_report_and_estimate.pdf p.1]:
- The roof covering is architectural asphalt shingle installed in 2016.
- Shingles on the south and west slopes show creased tabs, torn seal strips and missing shingles in a pattern consistent with wind uplift.
- The remaining shingles are in fair condition, with granule loss normal for their age, and show no general deterioration that would cause leaks.
- Water staining in the master bedroom and hallway ceilings lines up with the wind-damaged areas.
Mr. Ngata concluded that the damage to the south and west slopes and the interior water damage were caused by the September 18, 2025 windstorm "and not by wear and tear." He also found that because matching shingles are no longer produced, repairing the damaged slopes requires replacement of the full roof covering [engineer_report_and_estimate.pdf p.1].
Ridgeway Roofing and Restoration LLC (Dale Ridgeway, Florida licensed roofing contractor) prepared an estimate dated November 12, 2025 [engineer_report_and_estimate.pdf p.1]:
| Item | Amount | Source |
|---|
| Tear off and replace roof covering, 34 squares | $28,560.00 | [engineer_report_and_estimate.pdf p.1] |
| Replace underlayment and drip edge | $4,420.00 | [engineer_report_and_estimate.pdf p.1] |
| Remove and replace bedroom and hallway drywall ceilings | $3,980.00 | [engineer_report_and_estimate.pdf p.1] |
| Insulation replacement | $1,240.00 | [engineer_report_and_estimate.pdf p.1] |
| Interior painting | $2,160.00 | [engineer_report_and_estimate.pdf p.1] |
| Mold remediation, hallway attic area | $1,600.00 | [engineer_report_and_estimate.pdf p.1] |
| Total (as read from the bills) | $41,960.00 | [engineer_report_and_estimate.pdf p.1] |
On February 2, 2026, Mr. Montoya reported that the hallway ceiling is now sagging and that our clients see mold spots [claim_correspondence.pdf p.1]. [ADD: updated estimate or additional damages since November 12, 2025, if any]
Claim handling
| Date | Event | Source |
|---|
| September 19, 2025 | Mr. Montoya emails the loss report to Tarpon Reach claims and states a tarp is on the roof. | [claim_correspondence.pdf p.1] |
| September 22, 2025 | Tarpon Reach acknowledges the claim and assigns field adjuster Brian Kessler. | [claim_correspondence.pdf p.1] |
| October 6, 2025 | Mr. Kessler inspects the property. | [claim_correspondence.pdf p.1] |
| October 28, 2025 | Tarpon Reach estimates the covered loss at $6,680.22, pays $4,180.22 after the $2,500.00 deductible, and states the remaining roof covering damage is excluded as wear and tear and deterioration. | [claim_correspondence.pdf p.1] |
| November 14, 2025 | Mrs. Montoya disputes the estimate by certified mail and email, enclosing the Shellbank report (November 10, 2025) and the Ridgeway estimate (November 12, 2025), and asks Tarpon Reach to reconsider. | [claim_correspondence.pdf p.1] |
| December 3, 2025 | Mr. Montoya emails that our clients have not heard back and asks Tarpon Reach to confirm receipt. | [claim_correspondence.pdf p.1] |
| December 5, 2025 | Mr. Kessler replies by email: "Received. The file is under review. I will get back to you." | [claim_correspondence.pdf p.1] |
| January 9, 2026 | Mrs. Montoya leaves a voicemail for Mr. Kessler, noted in her call log. No return call. | [claim_correspondence.pdf p.1] |
| February 2, 2026 | Mr. Montoya emails that the hallway ceiling is sagging, mold spots are visible, and there is still no answer on the claim. | [claim_correspondence.pdf p.1] |
| As of March 1, 2026 | Our clients report no further response from Tarpon Reach. | [claim_correspondence.pdf p.1] |
Tarpon Reach stated its reason for limiting payment in its October 28, 2025 letter. Since our clients submitted an engineer's report and a contractor's estimate on November 14, 2025, the file shows only an acknowledgment of receipt and a statement that the file was under review. It shows no decision on that submission, no explanation of why the engineer's findings were not accepted, and no response to the later follow-up. Meanwhile, our clients report that the interior damage has continued to worsen [claim_correspondence.pdf p.1].
Demand
On behalf of Rafael Montoya and Ines Montoya, we demand that Tarpon Reach pay [ADD: demand amount] by [ADD: response deadline]. This amount reflects the documented loss under the Ridgeway estimate, less the applicable deductible and the amount Tarpon Reach has already paid [firm notes]; [engineer_report_and_estimate.pdf p.1]; [claim_correspondence.pdf p.1].
By the same date, please also provide in writing:
- Tarpon Reach's position on the Shellbank Structural Engineering report dated November 10, 2025 and the Ridgeway Roofing and Restoration estimate dated November 12, 2025, including the specific reasons for any part of the claim it declines to pay.
- A complete copy of the estimate underlying the $6,680.22 figure, and any inspection report, engineering report, photographs or other material on which Tarpon Reach relied in concluding that the remaining roof covering damage is due to wear and tear.
- [ADD: any other documents requested, such as the complete claim file or the certified policy]
Our clients reserve all rights under the policy and applicable law, including the right to supplement this demand for additional damage that has occurred or is discovered after the date of the Ridgeway estimate.
State rules
This claim arises under a Florida homeowners policy, and Tarpon Reach's handling of it is subject to Florida's rules governing insurers' claim handling and response times. [VERIFY: Florida rule on unfair claims handling and insurer response times]
Our clients' position is also that, because matching shingles are no longer produced, repair of the damaged slopes requires replacement of the full roof covering [engineer_report_and_estimate.pdf p.1]. [VERIFY: Florida rule on matching of replacement roofing materials]
[VERIFY: Florida rule on pre-suit notice requirements for property insurance disputes]
We look forward to your prompt response.
Sincerely,
Marcus T. Delacroix
Delacroix Bennett PLLC