Skip to content
Free Demand Writer
Menu
Free Demand Writer

Free Credit Reporting Error (FCRA) Demand Letter

A credit reporting error letter disputes specific inaccurate items on a consumer's credit report and demands that they be corrected or deleted. It can go to a credit bureau, to the furnisher that supplied the data, or to both. The federal Fair Credit Reporting Act requires reasonable investigation of disputes, and a letter that lists each item, says exactly what is wrong and attaches proof is the first step in building a record.

Free Demand Writer reads the report pages, payment records and prior dispute letters you upload and drafts an editable Word letter. It tables each disputed item with the report page it appears on, ties each one to its proof, and marks any state credit reporting law [VERIFY] for your attorney to confirm.

New to this kind of letter? Our guide explains what goes into a demand letter, when to send one and what happens next.

  • Free
  • No sign-up
  • Editable Word (.docx)
  • Files deleted after drafting

When to use this letter

Use this letter when a consumer's credit report shows items that the records prove are wrong. Typical cases:

  • An account paid in full or settled is still reported as unpaid or in collection.
  • Late payments are reported for months when the records show payment on time.
  • A debt discharged in bankruptcy still shows a balance due.
  • Accounts opened through identity theft appear on the report.
  • A mixed file shows another person's accounts, addresses or public records.
  • A bureau or furnisher verified an item after an earlier dispute without fixing it.

The federal Fair Credit Reporting Act sets duties for bureaus and furnishers, and some states add their own rules. Deadlines, remedies and the steps needed before a claim vary. Check them before sending.

What to upload

Upload up to 5 PDFs, 500 pages in total. The report pages and the proof for each item matter most. Redact full account and Social Security numbers before upload if you can.

Credit report pages
The pages from each bureau's report that show the disputed items, with the report date.
Payment proof
Bank statements, payoff letters, settlement agreements or receipts showing the account was paid or settled.
Court or bankruptcy records
A discharge order, dismissal or satisfied judgment that bears on the item.
Identity theft records
An identity theft report, police report or fraud affidavit, if accounts are not your client's.
Prior disputes
Earlier dispute letters, online dispute confirmations and the bureau's or furnisher's results.

What the draft includes

An editable Word letter built only from what your documents say. Missing facts become [ADD: …] placeholders, never guesses, and any law cited is marked [VERIFY].

  1. Please verify box. A short notice at the top reminding the reviewer that this is an unverified AI draft.
  2. Consumer identification. Name and current address, with placeholders for any identifiers the recipient requires.
  3. Disputed items table. Each item, the furnisher, what the report shows and what is correct, with the report page cited.
  4. Proof for each item. The record that shows each item is inaccurate, cited to its file and page.
  5. Prior disputes. Earlier disputes and the results, in date order, if your documents include them.
  6. Legal basis. The federal Fair Credit Reporting Act in general terms. Any state law is marked [VERIFY].
  7. The demand. Investigation, correction or deletion and an updated report by a set date. Any amount is a placeholder.

Before you send it

The result is an unverified AI draft for attorney review, not legal advice.

  • Confirm each disputed item against the report pages and the proof.
  • Decide whether to send to the bureau, the furnisher or both, and how to deliver it.
  • Check the state's credit reporting law and the steps needed before a claim.
  • Set the deadline and any amount, and remove the Please verify box.

Common mistakes

Bureaus process disputes in bulk. A vague letter is easy to answer with a form reply. These errors weaken a dispute most.

  • Disputing everything at once Disputing accurate items along with inaccurate ones can make the dispute look frivolous. List only the items the records prove wrong.
  • No proof attached Saying an account was paid is weaker than attaching the payoff letter. Tie each item to a document.
  • Sending only to the bureau Some duties apply to furnishers after a dispute through the bureau. Consider who should receive the letter.
  • Including full identifiers Full Social Security and account numbers in a letter create risk. Give only what the recipient needs.
  • Losing the paper trail Keep proof of delivery and every response. The dispute record matters if the matter goes further.

Free credit reporting error (fcra) demand letter template

Prefer to write it yourself? Download a plain Word template with fields to fill in. No AI, no email needed. Sample template, not legal advice.

Questions

Is the credit reporting error demand letter free?

Yes. No account and no payment.

Can it go to a furnisher instead of a credit bureau?

Yes. Tell us in the notes who the letter is for. If that is unclear, the draft leaves the recipient as a placeholder.

Does it cite sections of the FCRA?

No. It names the federal Fair Credit Reporting Act only in general terms and leaves legal citations for your attorney.

Will it include my client's Social Security number?

No. The draft never includes Social Security or full account numbers. It leaves placeholders for any identifiers you choose to add.

What happens to the documents I upload?

They are deleted as soon as the draft is generated. The Word file is deleted after 48 hours or 3 downloads.
Fictional sample

See a sample draft

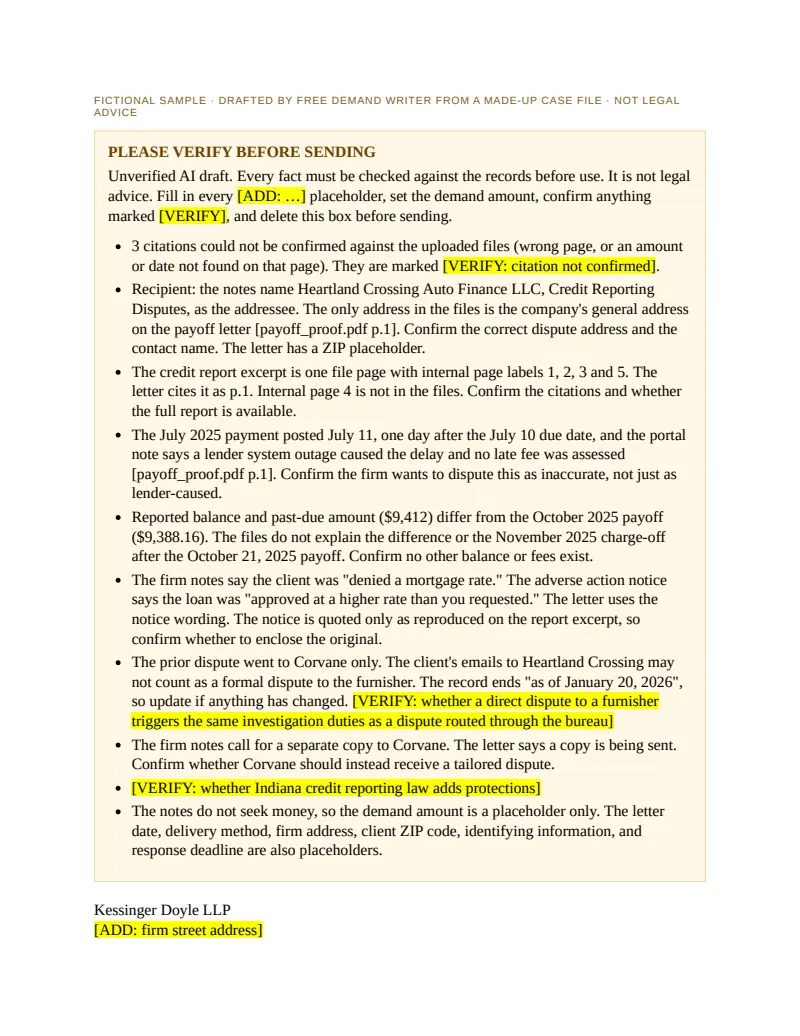
We made up a case file and ran it through Free Demand Writer, the same way your documents would be. This is the unedited draft. Everything in it is fictional: the people, the companies and the facts. An Indiana nurse paid off her auto loan in full, but the lender kept reporting it as charged off with a balance and a late payment, and a credit bureau verified the error after her own dispute.

Fictional case file: credit_report_excerpt.pdf, payoff_proof.pdf, prior_dispute.pdf · State: Indiana

Page 1 of a fictional sample credit reporting error (fcra) demand letter drafted by Free Demand Writer Download sample PDF

Fictional sample. Not legal advice. Your draft is built from your own documents.

Fictional sample · letter text

PLEASE VERIFY BEFORE SENDING

Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.

  • Recipient: the notes name Heartland Crossing Auto Finance LLC, Credit Reporting Disputes, as the addressee. The only address in the files is the company's general address on the payoff letter [payoff_proof.pdf p.1]. Confirm the correct dispute address and the contact name. The letter has a ZIP placeholder.
  • The credit report excerpt is one file page with internal page labels 1, 2, 3 and 5. The letter cites it as p.1. Internal page 4 is not in the files. Confirm the citations and whether the full report is available.
  • The July 2025 payment posted July 11, one day after the July 10 due date, and the portal note says a lender system outage caused the delay and no late fee was assessed [payoff_proof.pdf p.1]. Confirm the firm wants to dispute this as inaccurate, not just as lender-caused.
  • Reported balance and past-due amount ($9,412) differ from the October 2025 payoff ($9,388.16). The files do not explain the difference or the November 2025 charge-off after the October 21, 2025 payoff. Confirm no other balance or fees exist.
  • The firm notes say the client was "denied a mortgage rate." The adverse action notice says the loan was "approved at a higher rate than you requested." The letter uses the notice wording. The notice is quoted only as reproduced on the report excerpt, so confirm whether to enclose the original.
  • The prior dispute went to Corvane only. The client's emails to Heartland Crossing may not count as a formal dispute to the furnisher. The record ends "as of January 20, 2026", so update if anything has changed. [VERIFY: whether a direct dispute to a furnisher triggers the same investigation duties as a dispute routed through the bureau]
  • The firm notes call for a separate copy to Corvane. The letter says a copy is being sent. Confirm whether Corvane should instead receive a tailored dispute.
  • [VERIFY: whether Indiana credit reporting law adds protections]
  • The notes do not seek money, so the demand amount is a placeholder only. The letter date, delivery method, firm address, client ZIP code, identifying information, and response deadline are also placeholders.

Kessinger Doyle LLP
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]

[ADD: date]

VIA [ADD: delivery method]

[ADD: recipient name]
Credit Reporting Disputes
Heartland Crossing Auto Finance LLC
600 Commerce Loop [ADD: confirm dispute address]
Wabash Point, Indiana [ADD: ZIP]

Re: Dispute and Demand to Correct Inaccurate Credit Reporting. Consumer: Melissa J. Strand. Heartland Crossing auto loan ending 0838. Corvane Credit Reporting Inc. report number ending 55190. Claim/reference number: [ADD: claim or reference number]

Dear [ADD: recipient name]:

Introduction

This firm represents Melissa J. Strand, whose current address is 1907 Bur Oak Court, Fennimore Grove, Indiana [ADD: ZIP] [credit_report_excerpt.pdf p.1]. On her behalf, we dispute the items described below, which Heartland Crossing Auto Finance LLC has furnished to Corvane Credit Reporting Inc. regarding the auto installment loan ending 0838. Please direct all further communication about this matter to our office. For your identification purposes, [ADD: identifying information the recipient requires].

A copy of this letter is being sent separately to Corvane Credit Reporting Inc.

The disputed items

ItemFurnisherWhat the report showsWhat is correctSource
1. Account statusHeartland Crossing Auto Finance LLC"Charged off," date of status November 2025. November 2025 and December 2025 reported as charge-off.The loan was paid in full on October 21, 2025, before the reported status date.[credit_report_excerpt.pdf p.1]; [payoff_proof.pdf p.1]
2. Balance and past due amountHeartland Crossing Auto Finance LLCBalance $9,412; past due $9,412.Account balance is $0.00.[credit_report_excerpt.pdf p.1]; [payoff_proof.pdf p.1]
3. July 2025 payment historyHeartland Crossing Auto Finance LLCJuly 2025 reported as late.The July 10, 2025 autopay was returned because of a lender processing error and was reprocessed and posted July 11, 2025. No late fee was assessed.[credit_report_excerpt.pdf p.1]; [payoff_proof.pdf p.1]

The tradeline shows a date opened of March 2025 and an original amount of $24,800 [credit_report_excerpt.pdf p.1].

Why each item is inaccurate

Charge-off status and balance (Items 1 and 2). On October 14, 2025, Heartland Crossing issued a payoff quote of $9,388.16, good through October 24, 2025 [payoff_proof.pdf p.1]. Ms. Strand's bank statement shows an outgoing wire to Heartland Crossing Auto Finance LLC on October 21, 2025, referenced "Payoff 0838," in the amount of $9,388.16 [payoff_proof.pdf p.1]. Heartland Crossing's own paid in full letter, dated October 30, 2025, states that the loan ending 0838 "was paid in full on October 21, 2025," that the lien release was sent to the state title office, and that the account balance is $0.00 [payoff_proof.pdf p.1]. An account paid in full and carrying a $0.00 balance according to the furnisher's own letter cannot accurately be reported as charged off with a $9,412 balance and $9,412 past due [credit_report_excerpt.pdf p.1].

July 2025 late mark (Item 3). Payments are due on the 10th of each month [payoff_proof.pdf p.1]. Heartland Crossing's customer portal history shows that the scheduled July 10, 2025 autopay of $498.37 was "Returned, lender processing error, reprocessed," and that the autopay posted on July 11, 2025 [payoff_proof.pdf p.1]. The portal note states: "July payment was delayed by a Heartland Crossing system outage. No late fee assessed." [payoff_proof.pdf p.1]. The same history shows that all other payments from March to September 2025 posted on or before the due date [payoff_proof.pdf p.1]. A delay caused by the lender's own error should not be reported as a late payment by Ms. Strand.

Effect on our client. On December 2, 2025, Lakefront Home Mortgage Co. made an inquiry on Ms. Strand's file [credit_report_excerpt.pdf p.1]. In its December 9, 2025 adverse action notice, Lakefront stated that her loan "was approved at a higher rate than you requested," and gave as principal reasons "serious delinquency and a charged-off account reported by Corvane Credit Reporting Inc." [credit_report_excerpt.pdf p.1]. This is the harm the inaccurate reporting has already caused.

Prior disputes

  • November 24, 2025: Ms. Strand disputed the account ending 0838 online with Corvane, stating that the account is paid in full, was never charged off, and that the July payment was not late. She uploaded the October 30, 2025 paid in full letter and the bank statement page showing the October 21, 2025 wire [prior_dispute.pdf p.1].
  • December 19, 2025: Corvane reported the result "Verified as reported. The company that reported the information has certified that it is accurate." A comment, "Consumer disputes," was added [prior_dispute.pdf p.1]. The January 8, 2026 report carries the comment "Consumer disputes. Information verified as reported." [credit_report_excerpt.pdf p.1].
  • December 22, 2025: Ms. Strand emailed Heartland Crossing Customer Care, stated that the company had reported her paid loan as charged off, referred to the paid in full letter, and asked that the reporting be corrected [prior_dispute.pdf p.1].
  • January 5, 2026: Heartland Crossing Customer Care replied that it had forwarded the request to its credit reporting team and asked her to "allow time for review." [prior_dispute.pdf p.1].
  • No further response had been received as of January 20, 2026 [prior_dispute.pdf p.1].

The information remained on Ms. Strand's January 8, 2026 report despite the documents she submitted [credit_report_excerpt.pdf p.1].

Legal basis

The federal Fair Credit Reporting Act requires those who furnish information to consumer reporting agencies to report accurately, and requires reasonable procedures to assure accuracy and a reasonable investigation of consumer disputes. Heartland Crossing's own records show that the account was paid in full and that the July 2025 delay was caused by its own processing error. Continuing to report a charge-off, a balance, and a late payment in the face of those records is inconsistent with those obligations. [VERIFY: whether Indiana credit reporting law adds protections]

Demand

On behalf of Ms. Strand, we demand that Heartland Crossing Auto Finance LLC, by [ADD: response deadline]:

  • Conduct a reasonable investigation of each disputed item, taking into account the enclosed records, including its own paid in full letter and portal history.
  • Delete the charge-off status, the $9,412 balance and past due amount, and the July 2025 late payment mark for the account ending 0838.
  • Report the account as paid in full, with a $0.00 balance, paid on October 21, 2025.
  • Instruct Corvane Credit Reporting Inc. and every other consumer reporting agency to which it furnished this information to make the same corrections, and notify any recipient of the inaccurate information of the corrections.
  • Send our office a written statement of the results of its investigation and a copy of the corrected tradeline as it appears on an updated Corvane report.

Demand amount, if any: [ADD: demand amount, if any]. Ms. Strand reserves all rights and remedies under federal and state law, including for the harm already caused, and nothing in this letter waives any of them.

Enclosures:

  • Corvane credit report excerpt dated January 8, 2026 (credit_report_excerpt.pdf)
  • Payoff quote, paid in full letter, bank statement excerpt, and autopay history (payoff_proof.pdf)
  • Corvane dispute confirmation and result, and email correspondence with Heartland Crossing (prior_dispute.pdf)
  • [ADD: copy of the Lakefront Home Mortgage Co. adverse action notice dated December 9, 2025, if the firm wishes to enclose it]

Sincerely,

Rachel A. Kessinger
Kessinger Doyle LLP

cc: Corvane Credit Reporting Inc. (separate copy)