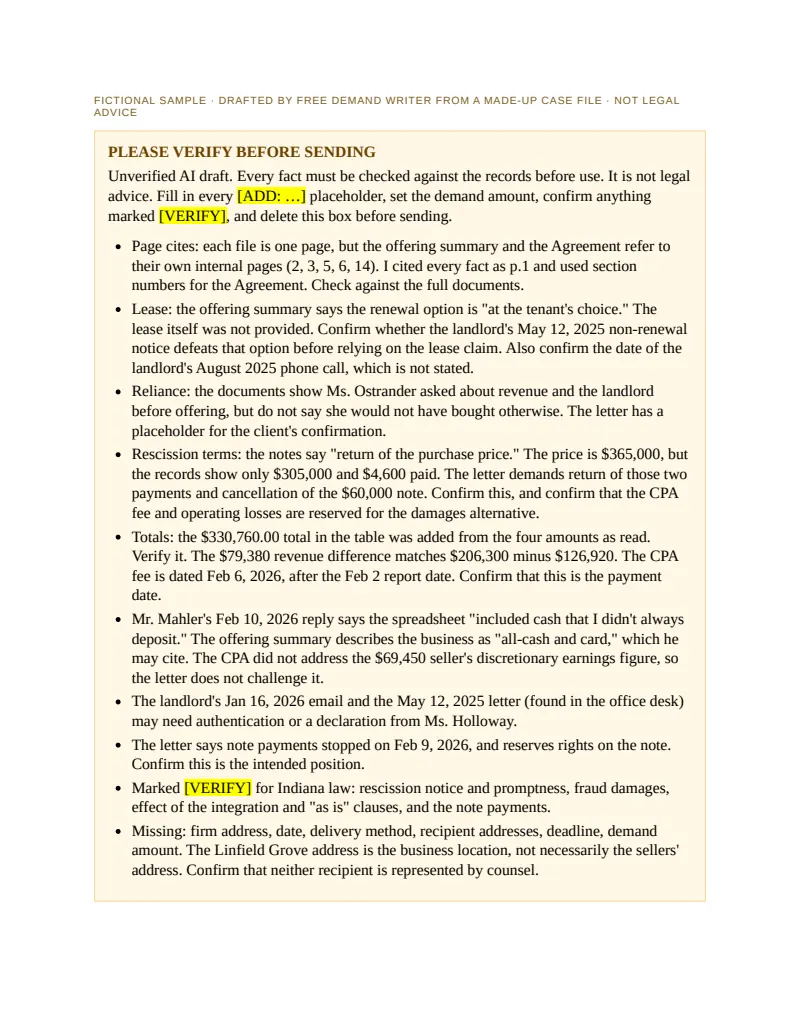
PLEASE VERIFY BEFORE SENDING
Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.
- Page cites: each file is one page, but the offering summary and the Agreement refer to their own internal pages (2, 3, 5, 6, 14). I cited every fact as p.1 and used section numbers for the Agreement. Check against the full documents.
- Lease: the offering summary says the renewal option is "at the tenant's choice." The lease itself was not provided. Confirm whether the landlord's May 12, 2025 non-renewal notice defeats that option before relying on the lease claim. Also confirm the date of the landlord's August 2025 phone call, which is not stated.
- Reliance: the documents show Ms. Ostrander asked about revenue and the landlord before offering, but do not say she would not have bought otherwise. The letter has a placeholder for the client's confirmation.
- Rescission terms: the notes say "return of the purchase price." The price is $365,000, but the records show only $305,000 and $4,600 paid. The letter demands return of those two payments and cancellation of the $60,000 note. Confirm this, and confirm that the CPA fee and operating losses are reserved for the damages alternative.
- Totals: the $330,760.00 total in the table was added from the four amounts as read. Verify it. The $79,380 revenue difference matches $206,300 minus $126,920. The CPA fee is dated Feb 6, 2026, after the Feb 2 report date. Confirm that this is the payment date.
- Mr. Mahler's Feb 10, 2026 reply says the spreadsheet "included cash that I didn't always deposit." The offering summary describes the business as "all-cash and card," which he may cite. The CPA did not address the $69,450 seller's discretionary earnings figure, so the letter does not challenge it.
- The landlord's Jan 16, 2026 email and the May 12, 2025 letter (found in the office desk) may need authentication or a declaration from Ms. Holloway.
- The letter says note payments stopped on Feb 9, 2026, and reserves rights on the note. Confirm this is the intended position.
- Marked [VERIFY] for Indiana law: rescission notice and promptness, fraud damages, effect of the integration and "as is" clauses, and the note payments.
- Missing: firm address, date, delivery method, recipient addresses, deadline, demand amount. The Linfield Grove address is the business location, not necessarily the sellers' address. Confirm that neither recipient is represented by counsel.
Strickland Oduya LLP
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]
[ADD: date]
VIA [ADD: delivery method]
Curtis Mahler
[ADD: street address]
[ADD: city, state ZIP]
Spinwell Laundry LLC
Attn: Curtis Mahler, Sole Member
[ADD: street address]
[ADD: city, state ZIP]
Re: Misrepresentations in the sale of Spinwell Laundry, 1915 Coldwater Pike, Linfield Grove, Indiana; Asset Purchase Agreement dated September 5, 2025 (closed September 22, 2025); Our clients: Ostrander Ventures LLC and Nadine Ostrander; Demand for rescission
Dear Mr. Mahler:
Introduction
We represent Ostrander Ventures LLC and its member, Nadine Ostrander, in connection with their purchase of the Spinwell Laundry business from Spinwell Laundry LLC and you, under the Asset Purchase Agreement dated September 5, 2025, which closed on September 22, 2025 [asset_purchase_agreement.pdf p.1; firm notes]. This letter explains how you and Spinwell Laundry LLC misrepresented the business's revenue and the status of its lease, and demands rescission of the purchase. Please direct all further communication about this matter to us.
The transaction
Ostrander Ventures LLC bought the Spinwell Laundry business, which was offered with 28 washers, 22 dryers and a card payment system [offering_summary_and_emails.pdf p.1]. The purchase price was $365,000, paid as $305,000 at closing by wire and a $60,000 promissory note from the buyer to the seller [asset_purchase_agreement.pdf p.1, Section 2.1]. You signed the Agreement for Spinwell Laundry LLC and individually [asset_purchase_agreement.pdf p.1].
The Agreement contains the following terms:
- Section 4.3 (Financial information): you represented that the revenue spreadsheet delivered on August 5, 2025 "is true and correct and was prepared from the business's bank and card processing records" [asset_purchase_agreement.pdf p.1].
- Section 4.7 (Lease): you represented that the seller "has received no notice from the landlord of any default, termination, or intent not to renew or extend the lease" [asset_purchase_agreement.pdf p.1].
- Section 4.12 (Equipment condition): the equipment is sold "as is" except for the representations in Section 4 [asset_purchase_agreement.pdf p.1].
- Section 9.4 (Entire agreement): the Agreement is the entire agreement and "replaces all prior discussions" [asset_purchase_agreement.pdf p.1].
- Section 9.6 (Survival): the seller's Section 4 representations survive closing [asset_purchase_agreement.pdf p.1].
The representations
You made the following statements to Ms. Ostrander before she signed the Agreement:
- Offering summary (July 8, 2025), prepared by you: "Gross revenue, January 1 through June 30, 2025: $206,300 (annualized $412,600)" [offering_summary_and_emails.pdf p.1].
- Email of August 5, 2025, answering Ms. Ostrander's August 4 question whether the revenue was supported by the bank deposits: "the revenue number comes straight from the deposits and the card processor reports" [offering_summary_and_emails.pdf p.1].
- Revenue spreadsheet (sent August 5, 2025), prepared by you: monthly gross revenue for January through June 2025 totaling $206,300 [offering_summary_and_emails.pdf p.1].
- Agreement, Section 4.3: the spreadsheet is true and correct and was prepared from the bank and card processing records [asset_purchase_agreement.pdf p.1].
- Offering summary, lease: "Current lease runs through December 31, 2026 with a renewal option for an additional five-year term at the tenant's choice" [offering_summary_and_emails.pdf p.1].
- Email of August 5, 2025, answering Ms. Ostrander's August 4 question whether there was anything about the lease or landlord she should know: "No issues with the landlord at all. He has always been happy to renew" [offering_summary_and_emails.pdf p.1].
- Agreement, Section 4.7: no notice from the landlord of an intent not to renew or extend the lease [asset_purchase_agreement.pdf p.1].
You did not disclose that the landlord, Holloway Creek Properties LLC, had written to you on May 12, 2025 that it "will not renew or extend the lease for 1915 Coldwater Pike when it ends on December 31, 2026" because it planned to redevelop the site. The letter was sent by certified mail, and the return receipt was signed by you on May 15, 2025 [accountant_report_and_landlord_letter.pdf p.1]. The landlord's manager also states that she told you again by phone in August 2025 [accountant_report_and_landlord_letter.pdf p.1]. You therefore had the landlord's notice nearly three months before your August 5, 2025 email and almost four months before you signed the Agreement on September 5, 2025.
The true facts
Revenue. Kerrigan & Patel CPAs compared your spreadsheet for January through June 2025 with the bank statements and card processor reports for the same months. Revenue on your spreadsheet was $206,300. Revenue supported by bank deposits and card processor reports was $126,920, a difference of $79,380 [accountant_report_and_landlord_letter.pdf p.1]. Every month on your spreadsheet was higher than the deposits for that month, by between $9,800 and $17,200, and the accountants found no other bank account in the records [accountant_report_and_landlord_letter.pdf p.1].
In your email of February 10, 2026, you wrote that "the spreadsheet included cash that I didn't always deposit" [payments_and_losses.pdf p.1]. That explanation does not match what you told Ms. Ostrander on August 5, 2025, that the figure came "straight from the deposits and the card processor reports," or what you represented in Section 4.3, that the spreadsheet was prepared from bank and card processing records. Your email also does not identify any amount of cash or any record of it.
Lease. The landlord had given formal written notice on May 12, 2025 that it would not renew or extend the lease, and you received it on May 15, 2025 [accountant_report_and_landlord_letter.pdf p.1]. On January 16, 2026, the landlord's manager confirmed to Ms. Ostrander that she sent the notice in May 2025, told you again by phone in August 2025, and that "the lease will end on December 31, 2026" [accountant_report_and_landlord_letter.pdf p.1]. Your statements that there were "no issues with the landlord at all" and that the seller had received no notice of an intent not to renew are inconsistent with that notice. Your February 10, 2026 comment that the landlord "changes his mind all the time" does not alter the fact that you received the written notice before you made those statements [payments_and_losses.pdf p.1].
Reliance and harm
Before making an offer, Ms. Ostrander asked you in writing whether the revenue was supported by the bank deposits and whether there was anything about the lease or landlord she should know [offering_summary_and_emails.pdf p.1]. You answered both questions on August 5, 2025, and the Agreement she then signed repeated your representations on both subjects in Sections 4.3 and 4.7 [asset_purchase_agreement.pdf p.1]. [ADD: confirm with client how she relied on these statements in deciding to buy and close, and what she would have done had she known the true facts.]
Ostrander Ventures LLC noticed that monthly deposits from October to December 2025 were far below your spreadsheet. On January 14, 2026 Ms. Ostrander found the landlord's May 12, 2025 letter in the office desk. The landlord confirmed the non-renewal on January 16, 2026, and the accountants confirmed the revenue gap on February 2, 2026 [payments_and_losses.pdf p.1; accountant_report_and_landlord_letter.pdf p.1]. On February 9, 2026 she wrote to you, described both problems, and said she wanted to unwind the purchase. She stopped payments on the promissory note that day [payments_and_losses.pdf p.1]. You replied on February 10, 2026 that the business was bought "as is" and that you expect the note payments to continue [payments_and_losses.pdf p.1].
Our clients' payments and losses are:
| Item | Date | Amount | Source |
|---|
| Closing wire to Spinwell Laundry LLC | Sep 22, 2025 | $305,000.00 | [payments_and_losses.pdf p.1] |
| Payments on $60,000 promissory note | Oct 2025 to Jan 2026 | $4,600.00 | [payments_and_losses.pdf p.1] |
| Kerrigan & Patel revenue review fee | Feb 6, 2026 | $3,200.00 | [payments_and_losses.pdf p.1] |
| Operating losses funded by buyer | Oct 2025 to Jan 2026 | $17,960.00 | [payments_and_losses.pdf p.1] |
| Total (as read from the records) | | $330,760.00 | |
Demand
Our clients elect to rescind the purchase. We demand that, by [ADD: response deadline], you and Spinwell Laundry LLC:
- return the $305,000.00 closing payment and the $4,600.00 paid on the promissory note [payments_and_losses.pdf p.1];
- cancel the $60,000 promissory note and release Ostrander Ventures LLC from further payments under it [asset_purchase_agreement.pdf p.1] [ADD: confirm treatment of the note]; and
- confirm in writing a date and method for Ostrander Ventures LLC to return the business and its assets to Spinwell Laundry LLC [ADD: return logistics and inventory of assets].
In the alternative, if you do not agree to rescission, our clients demand payment of [ADD: demand amount] by the same date as damages for the misrepresentations described above.
Our clients reserve the right to seek the other losses listed in the table above, including the review fee and operating losses, together with all other remedies available to them. Ostrander Ventures LLC stopped payments on the promissory note on February 9, 2026, and nothing in this letter waives any position regarding the note.
You and Spinwell Laundry LLC must preserve all documents, data and messages relating to this matter, including:
- bank statements, deposit records and card processor reports for the business;
- any records of cash receipts, and any other account into which business revenue was received;
- all drafts and source files for the revenue spreadsheet and the offering summary;
- the lease, and all communications with Holloway Creek Properties LLC or Gail Holloway, including the May 12, 2025 notice, the certified mail receipt and any record of the August 2025 call; and
- all communications with Ms. Ostrander.
Our clients reserve all rights and remedies, and nothing in this letter waives any of them.
State rules
We have prepared this demand under Indiana law. Our clients' claims and remedies, including rescission and, in the alternative, damages, are governed by Indiana's rules on fraud and misrepresentation [VERIFY: Indiana rule on fraud damages]. Our clients are acting promptly after discovering the facts, and this letter is their notice of rescission [VERIFY: Indiana rule on notice of rescission]. We do not agree that the "as is" language in Section 4.12 or the entire-agreement clause in Section 9.4 bars these claims. The misrepresentations at issue concern revenue and the lease, which are the subject of express representations in Sections 4.3 and 4.7 that survive closing under Section 9.6 [asset_purchase_agreement.pdf p.1] [VERIFY: Indiana rule on effect of integration and "as is" clauses on misrepresentation claims]. Our clients' position on the promissory note is reserved [VERIFY: Indiana rule on nonpayment of a note when the underlying sale is subject to rescission].
We look forward to your response by [ADD: response deadline].
Sincerely,
Malcolm J. Strickland
Strickland Oduya LLP