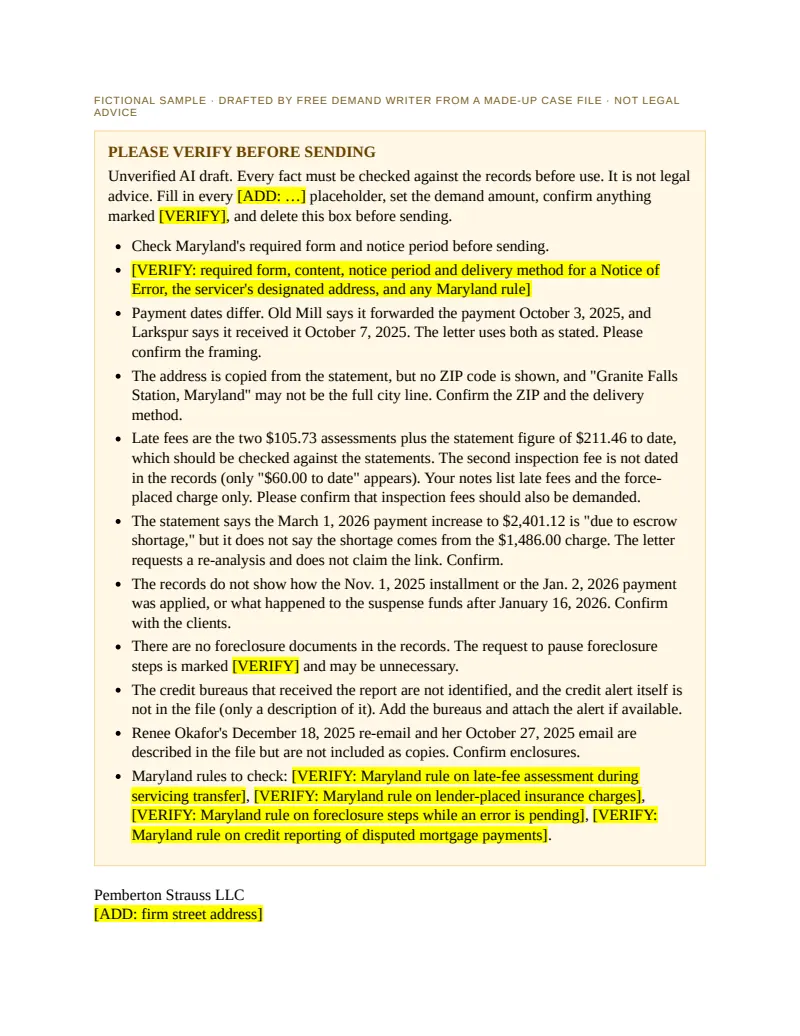
PLEASE VERIFY BEFORE SENDING
Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.
- Check Maryland's required form and notice period before sending.
- [VERIFY: required form, content, notice period and delivery method for a Notice of Error, the servicer's designated address, and any Maryland rule]
- Payment dates differ. Old Mill says it forwarded the payment October 3, 2025, and Larkspur says it received it October 7, 2025. The letter uses both as stated. Please confirm the framing.
- The address is copied from the statement, but no ZIP code is shown, and "Granite Falls Station, Maryland" may not be the full city line. Confirm the ZIP and the delivery method.
- Late fees are the two $105.73 assessments plus the statement figure of $211.46 to date, which should be checked against the statements. The second inspection fee is not dated in the records (only "$60.00 to date" appears). Your notes list late fees and the force-placed charge only. Please confirm that inspection fees should also be demanded.
- The statement says the March 1, 2026 payment increase to $2,401.12 is "due to escrow shortage," but it does not say the shortage comes from the $1,486.00 charge. The letter requests a re-analysis and does not claim the link. Confirm.
- The records do not show how the Nov. 1, 2025 installment or the Jan. 2, 2026 payment was applied, or what happened to the suspense funds after January 16, 2026. Confirm with the clients.
- There are no foreclosure documents in the records. The request to pause foreclosure steps is marked [VERIFY] and may be unnecessary.
- The credit bureaus that received the report are not identified, and the credit alert itself is not in the file (only a description of it). Add the bureaus and attach the alert if available.
- Renee Okafor's December 18, 2025 re-email and her October 27, 2025 email are described in the file but are not included as copies. Confirm enclosures.
- Maryland rules to check: [VERIFY: Maryland rule on late-fee assessment during servicing transfer], [VERIFY: Maryland rule on lender-placed insurance charges], [VERIFY: Maryland rule on foreclosure steps while an error is pending], [VERIFY: Maryland rule on credit reporting of disputed mortgage payments].
Pemberton Strauss LLC
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]
[ADD: date]
VIA [ADD: delivery method]
Larkspur Home Loan Servicing
Attn: Notice of Error Unit
P.O. Box 70218
Granite Falls Station, Maryland [ADD: ZIP] [mortgage_statements.pdf p.1]
Re: Notice of Error. Thomas Okafor and Renee Okafor; Loan number ending 4471 [ADD: full loan number]; 1127 Hawthorne Glen Road, Elkmont Mills, Maryland
Dear Notice of Error Unit:
Introduction
We represent Thomas Okafor and Renee Okafor, the borrowers on the mortgage loan ending 4471 secured by the property at 1127 Hawthorne Glen Road, Elkmont Mills, Maryland [mortgage_statements.pdf p.1; firm notes]. This letter is a Notice of Error under the Real Estate Settlement Procedures Act. Your statements direct that notices of error be sent to the Notice of Error Unit at the address above, and we are sending it there [mortgage_statements.pdf p.1]. Please direct all further communication about this matter to our office.
The error
Our clients' servicing was transferred from Old Mill Mortgage Company to Larkspur Home Loan Servicing effective October 1, 2025. The transfer notice dated September 12, 2025 stated that Old Mill would stop accepting payments on September 30, 2025, and that "a payment sent to Old Mill on time will not be treated as late and will be forwarded to Larkspur" [transfer_notice_and_proof_of_payment.pdf p.1].
1. The October 1, 2025 payment was made on time and was not applied. On September 26, 2025, our clients' bank account was debited $2,114.67 by Old Mill for the October 1, 2025 installment [transfer_notice_and_proof_of_payment.pdf p.1]. Old Mill confirmed in a letter dated October 20, 2025 that it received the payment on September 26, 2025 and forwarded it to Larkspur on October 3, 2025 by check no. 558104 [transfer_notice_and_proof_of_payment.pdf p.1]. Our clients' October bank statement shows no other mortgage debit [transfer_notice_and_proof_of_payment.pdf p.1].
Larkspur's January 9, 2026 letter states that it received the funds from the prior servicer on October 7, 2025 and placed them in suspense "because they were received after the transfer date," and that the funds "will be applied when a full contractual payment is available" [servicer_letters.pdf p.1]. Your statements nonetheless continue to show the October 1, 2025 installment of $2,114.67 as past due, and show $2,114.67 in unapplied funds (suspense) on statements dated November 17 and December 17, 2025 [mortgage_statements.pdf p.1]. The December 17, 2025 statement also shows that our clients' November payment, received November 28, 2025, was applied to the October 1 installment [mortgage_statements.pdf p.1].
2. Late fees and inspection fees assessed as a result. Larkspur assessed a late fee of $105.73 on October 16, 2025, a property inspection fee of $30.00 on October 28, 2025, and a second late fee of $105.73 on December 16, 2025 [mortgage_statements.pdf p.1]. The January 16, 2026 statement shows late fees to date of $211.46 and inspection fees to date of $60.00 [mortgage_statements.pdf p.1]. Larkspur's January 9, 2026 letter states that the late fees "were assessed according to the terms of your note" [servicer_letters.pdf p.1]. Our clients' payment was made before the transfer date and the transfer notice stated that it would not be treated as late, so these fees were not properly assessed.
3. Lender-placed insurance was purchased although coverage was in force. Our clients' homeowners policy with Chesapeake Bayline Mutual Insurance (policy number ending 3318) has a policy period of July 14, 2025 to July 14, 2026, with dwelling coverage of $412,000. The annual premium of $1,322.00 was paid in full by Old Mill from escrow on July 2, 2025 [insurance_records.pdf p.1]. At our clients' request, the mortgagee clause was updated to name Larkspur on October 22, 2025 [insurance_records.pdf p.1].
Larkspur sent a first notice on October 24, 2025 stating that it had no evidence of hazard insurance [insurance_records.pdf p.1]. On October 27, 2025, Renee Okafor emailed Larkspur the declarations page, stating that the policy was in force through July 14, 2026 and that the mortgagee clause now named Larkspur [insurance_records.pdf p.1]. Larkspur sent a second notice on November 21, 2025 stating that it had not received proof of coverage [insurance_records.pdf p.1]. On December 9, 2025, Larkspur notified our clients that it had purchased hazard insurance from Ironleaf Specialty Insurance with an annual premium of $1,486.00 and coverage of $389,500, charged to escrow [insurance_records.pdf p.1]. When Ms. Okafor called on December 18, 2025, the representative said the declarations page was "not indexed," and Ms. Okafor emailed it again that day [servicer_letters.pdf p.1]. [VERIFY: Maryland rule on lender-placed insurance charges]
4. Escrow shortage and payment increase. The December 17, 2025 statement shows the $1,486.00 charge to escrow and an escrow balance of negative $912.44 [mortgage_statements.pdf p.1]. The January 16, 2026 statement shows a new monthly payment of $2,401.12 effective March 1, 2026 "due to escrow shortage" [mortgage_statements.pdf p.1]. The escrow account should be re-analyzed once the lender-placed insurance charge is removed.
5. Negative credit reporting. Larkspur sent a Notice of Delinquency on January 20, 2026 stating that delinquent payments may be reported to the credit bureaus [servicer_letters.pdf p.1]. On February 4, 2026, Thomas Okafor received a credit monitoring alert that the mortgage account with Larkspur "was reported as past due" [servicer_letters.pdf p.1].
The errors are summarized below.
| Date | Item | Servicer shows | Correct | Source |
|---|
| September 26, 2025 | October 1, 2025 installment, $2,114.67 | Funds held in suspense; October 1 installment past due | Apply as a timely October 1, 2025 payment | [transfer_notice_and_proof_of_payment.pdf p.1; mortgage_statements.pdf p.1] |
| October 16, 2025 | Late fee | $105.73 assessed | Reverse | [mortgage_statements.pdf p.1] |
| October 28, 2025 | Property inspection fee | $30.00 assessed | Reverse | [mortgage_statements.pdf p.1] |
| December 16, 2025 | Late fee | $105.73 assessed | Reverse | [mortgage_statements.pdf p.1] |
| [ADD: date of second inspection fee] | Property inspection fee | Inspection fees to date $60.00 | Reverse | [mortgage_statements.pdf p.1] |
| December 9, 2025 | Lender-placed hazard insurance premium charged to escrow | $1,486.00 | Reverse; coverage was in force | [mortgage_statements.pdf p.1; insurance_records.pdf p.1] |
| December 17, 2025 | Escrow balance | Negative $912.44 | Re-analyze after reversal | [mortgage_statements.pdf p.1] |
| Effective March 1, 2026 | Monthly payment | $2,401.12 "due to escrow shortage" | Recalculate after re-analysis | [mortgage_statements.pdf p.1] |
| February 4, 2026 | Credit reporting | Reported as past due | Withdraw | [servicer_letters.pdf p.1] |
Prior contact
Our clients have raised these errors with Larkspur several times, in date order:
- October 24, 2025: Larkspur sent a first notice stating it had no evidence of hazard insurance [insurance_records.pdf p.1].
- October 27, 2025: Renee Okafor emailed the declarations page to Larkspur [insurance_records.pdf p.1].
- November 20, 2025: Ms. Okafor called Larkspur and spoke with a representative identified as "Jordan," ID LHS-882. She explained that Old Mill had forwarded the October payment. The representative said the funds were in suspense and would be applied after research (reference no. 5521-0948) [servicer_letters.pdf p.1].
- November 21, 2025: Larkspur sent a second notice stating it had not received proof of coverage [insurance_records.pdf p.1].
- December 9, 2025: Larkspur sent notice of the lender-placed insurance [insurance_records.pdf p.1].
- December 18, 2025: Ms. Okafor called and spoke with a representative identified as "Alicia," ID LHS-604, who said the declarations page was "not indexed." Ms. Okafor emailed it again the same day [servicer_letters.pdf p.1].
- January 9, 2026: Larkspur's Customer Advocacy Department wrote that the funds were in suspense, that late fees were assessed according to the note, and that it was reviewing the insurance documents and would send a separate response [servicer_letters.pdf p.1].
- January 20, 2026: Larkspur sent a Notice of Delinquency [servicer_letters.pdf p.1].
- As of February 10, 2026, our clients had received no response on the insurance issue [servicer_letters.pdf p.1].
Request
On behalf of Mr. and Mrs. Okafor, we ask that Larkspur do the following:
- Apply the $2,114.67 received from Old Mill as the October 1, 2025 installment, effective as of its receipt, and correct the loan history, including the application of later payments and the suspense balance.
- Reverse the late fees of $105.73 assessed October 16, 2025 and December 16, 2025, and any other late fee assessed as a result of the October 1, 2025 installment. Also reverse the property inspection fees and any other fee that followed from the same error.
- Reverse the $1,486.00 lender-placed insurance charge, cancel the Ironleaf Specialty Insurance policy, and credit our clients' escrow account with any related charges and interest.
- Re-analyze the escrow account and recalculate the monthly payment now stated as $2,401.12 effective March 1, 2026.
- Refund or credit our clients [ADD: demand amount, if any] for the amounts above that they have paid or that remain charged to their account.
- Withdraw and correct all negative credit reporting about this loan to every consumer reporting agency [ADD: names of credit bureaus, if known], and send us written confirmation.
- Refrain from any foreclosure step or other collection action tied to these errors while this notice is being resolved [VERIFY: Maryland rule on foreclosure steps while an error is pending].
- Send us copies of the documents you relied on, including the complete payment history and transaction history for the loan, your records of receipt of Old Mill check no. 558104, your suspense account records, the basis for each fee, your insurance tracking and correspondence records, the lender-placed insurance policy and escrow analyses, and your credit reporting records [VERIFY: Maryland rule on credit reporting of disputed mortgage payments].
Please respond to this notice in writing, addressed to our office, by [ADD: response deadline].
Sincerely,
Adrienne K. Strauss
Pemberton Strauss LLC