Skip to content
Free Demand Writer
Menu
Free Demand Writer

Free Personal Guarantee Enforcement Demand Letter

When a business borrower or commercial tenant defaults, a personal guaranty may let the lender or landlord collect from the individual who signed it. A demand letter to the guarantor sets out the guaranty's terms, the default and the amount owed, and asks the guarantor to pay before the creditor files suit.

Free Demand Writer reads the guaranty, the underlying loan or lease, the account history and any default notices you upload and drafts the letter in Word for the creditor. It quotes the guaranty's key terms with page citations, itemizes the balance in a table, and marks the guaranty's scope, waivers and notice requirements for you to verify.

New to this kind of letter? Our guide explains what goes into a demand letter, when to send one and what happens next.

  • Free
  • No sign-up
  • Editable Word (.docx)
  • Files deleted after drafting

When to use this letter

Use this letter when the primary obligor has defaulted and the creditor wants payment from the individual guarantor. Typical cases:

  • A business loan or line of credit is in default and an owner signed a personal guaranty.
  • A commercial tenant stopped paying rent or abandoned the premises, and a principal guaranteed the lease.
  • An equipment lease or vendor credit account was personally guaranteed and is past due.
  • The borrower has closed, filed for bankruptcy or stopped responding.
  • Earlier demands to the borrower have gone unanswered.

Guaranties vary widely. Some are unconditional, others are capped or limited to certain obligations, and some require notice or a demand on the borrower first. Your attorney must check the guaranty's terms and the governing law before sending.

What to upload

Upload up to 5 PDFs, 500 pages in total. The signed guaranty matters most, followed by the agreement it guarantees.

The guaranty
The signed guaranty, with any amendments, reaffirmations or releases.
The underlying agreement
The loan agreement, note, lease or credit application the guaranty covers.
Account history
Payment history, rent ledger or statement of account showing the balance.
Default notices
Notices and demands sent to the borrower or tenant, with proof of delivery.
Collateral records
Any record of collateral sold or applied to the balance, if relevant.

What the draft includes

An editable Word letter built only from what your documents say. Missing facts become [ADD: …] placeholders, never guesses, and any law cited is marked [VERIFY].

  1. Please verify box. A short notice at the top reminding the reviewer that this is an unverified AI draft.
  2. The guaranty. Key terms quoted with the page: scope, limits, waivers, notice and attorney fee clauses.
  3. The underlying obligation. The loan, lease or credit agreement and what the borrower agreed to pay.
  4. The default. What the borrower failed to pay or do and any notices already sent, in date order.
  5. Amount owed. A table of principal, interest, charges and fees as the documents show them, with any guaranty cap applied.
  6. The demand. Payment under the guaranty, with the amount, deadline and payment instructions as placeholders.
  7. Points to verify. Guaranty scope, waivers, notice requirements and state rules marked [VERIFY].

Before you send it

The result is an unverified AI draft for attorney review, not legal advice.

  • Read the guaranty in full, including any cap, time limit and covered obligations.
  • Check whether the guaranty requires notice to the guarantor or a demand on the borrower first.
  • Confirm the balance against the ledger and apply any payments or collateral credits.
  • Check for changes to the underlying agreement that the guarantor did not approve.
  • Set the amount and deadline, and remove the Please verify box.

Common mistakes

Guarantors often defend on the guaranty's own terms. These are the errors most worth fixing before the letter goes out.

  • Demanding more than the guaranty covers A limited guaranty may cap the amount or cover only certain obligations. Apply the limits before stating the balance.
  • Skipping required notice Some guaranties require notice of default or a demand on the borrower before the guarantor is liable. Follow the guaranty's notice terms.
  • Overlooking amendments Loan modifications or lease changes made without the guarantor's consent can affect liability. Check the full paper trail.
  • Leaving out credits Payments, security deposits and collateral proceeds should reduce the balance. An overstated demand invites a dispute.

Free personal guarantee enforcement demand letter template

Prefer to write it yourself? Download a plain Word template with fields to fill in. No AI, no email needed. Sample template, not legal advice.

Questions

Is the personal guarantee demand letter free?

Yes. No account and no payment.

Should the borrower get a copy?

If your notes say so, the draft adds the borrower as a copy recipient. Otherwise it is addressed to the guarantor only.

Does it work for lease guaranties?

Yes. Upload the lease, the guaranty and the rent ledger, and the draft itemizes the rent and charges the documents show.

Will it decide whether the guaranty is enforceable?

No. The draft quotes the terms and marks the scope, waivers and governing law [VERIFY] for your attorney to assess.

What happens to the documents I upload?

They are deleted as soon as the draft is generated. The Word file is deleted after 48 hours or 3 downloads.
Fictional sample

See a sample draft

We made up a case file and ran it through Free Demand Writer, the same way your documents would be. This is the unedited draft. Everything in it is fictional: the people, the companies and the facts. An Iowa community bank's equipment loan to a bakery went into default, the bank sold the collateral at auction, and the owner who signed an unconditional personal guaranty has not paid the remaining balance.

Fictional case file: commercial_guaranty.pdf, promissory_note_excerpt.pdf, loan_payment_history.pdf, default_notices.pdf · State: Iowa

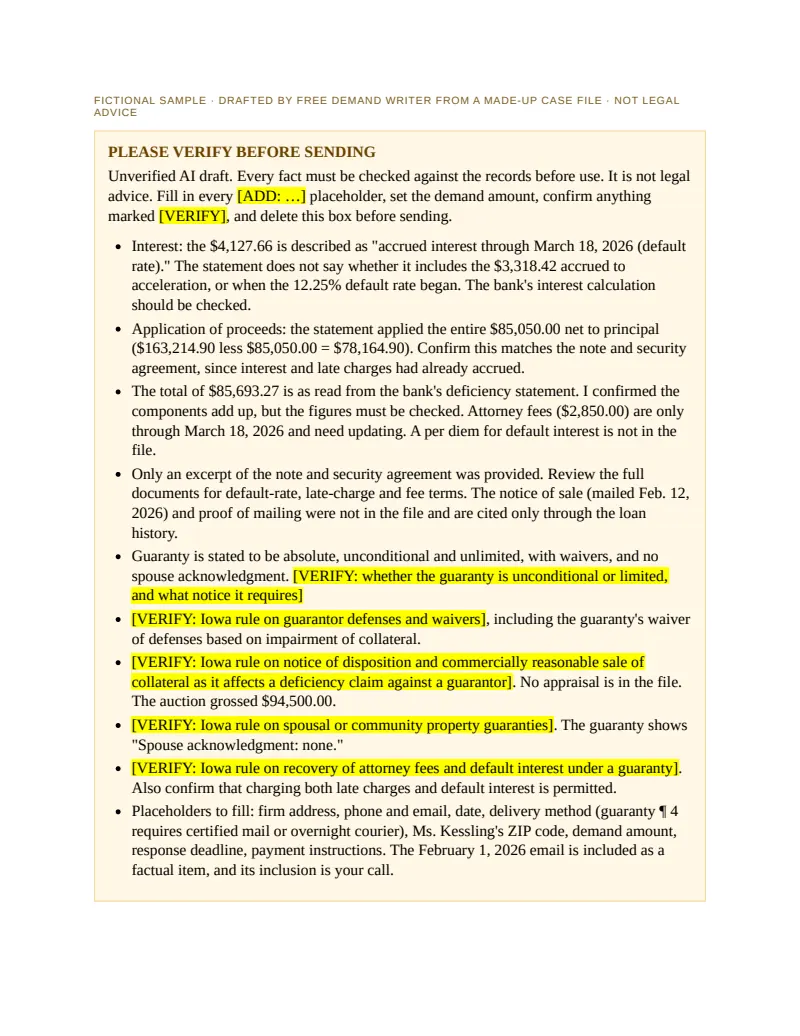
Page 1 of a fictional sample personal guarantee enforcement demand letter drafted by Free Demand Writer Download sample PDF

Fictional sample. Not legal advice. Your draft is built from your own documents.

Fictional sample · letter text

PLEASE VERIFY BEFORE SENDING

Unverified AI draft. Every fact must be checked against the records before use. It is not legal advice. Fill in every [ADD: …] placeholder, set the demand amount, confirm anything marked [VERIFY], and delete this box before sending.

  • Interest: the $4,127.66 is described as "accrued interest through March 18, 2026 (default rate)." The statement does not say whether it includes the $3,318.42 accrued to acceleration, or when the 12.25% default rate began. The bank's interest calculation should be checked.
  • Application of proceeds: the statement applied the entire $85,050.00 net to principal ($163,214.90 less $85,050.00 = $78,164.90). Confirm this matches the note and security agreement, since interest and late charges had already accrued.
  • The total of $85,693.27 is as read from the bank's deficiency statement. I confirmed the components add up, but the figures must be checked. Attorney fees ($2,850.00) are only through March 18, 2026 and need updating. A per diem for default interest is not in the file.
  • Only an excerpt of the note and security agreement was provided. Review the full documents for default-rate, late-charge and fee terms. The notice of sale (mailed Feb. 12, 2026) and proof of mailing were not in the file and are cited only through the loan history.
  • Guaranty is stated to be absolute, unconditional and unlimited, with waivers, and no spouse acknowledgment. [VERIFY: whether the guaranty is unconditional or limited, and what notice it requires]
  • [VERIFY: Iowa rule on guarantor defenses and waivers], including the guaranty's waiver of defenses based on impairment of collateral.
  • [VERIFY: Iowa rule on notice of disposition and commercially reasonable sale of collateral as it affects a deficiency claim against a guarantor]. No appraisal is in the file. The auction grossed $94,500.00.
  • [VERIFY: Iowa rule on spousal or community property guaranties]. The guaranty shows "Spouse acknowledgment: none."
  • [VERIFY: Iowa rule on recovery of attorney fees and default interest under a guaranty]. Also confirm that charging both late charges and default interest is permitted.
  • Placeholders to fill: firm address, phone and email, date, delivery method (guaranty ¶ 4 requires certified mail or overnight courier), Ms. Kessling's ZIP code, demand amount, response deadline, payment instructions. The February 1, 2026 email is included as a factual item, and its inclusion is your call.

Thorsen Gable PC
[ADD: firm street address]
[ADD: city, state ZIP]
[ADD: phone] · [ADD: email]

[ADD: date]

VIA [ADD: certified mail or overnight courier, per Guaranty ¶ 4]

Nora Kessling
57 Orchard Hill Lane
Linden Ford, Iowa [ADD: ZIP]

Re: Demand for Payment under Commercial Guaranty dated April 7, 2025 – Borrower: Harvest Table Bakery LLC – Cedar Mill Community Bank loan ending 5583

Dear Ms. Kessling:

Introduction

We represent Cedar Mill Community Bank (the "Bank") [firm notes]. This letter concerns the Commercial Guaranty dated April 7, 2025, which you signed individually, guaranteeing the obligations of Harvest Table Bakery LLC (the "Borrower") to the Bank [commercial_guaranty.pdf p.1]. Those obligations include the Promissory Note dated April 7, 2025, in the principal amount of $180,000.00, for the purchase of commercial baking equipment [promissory_note_excerpt.pdf p.1]. The Note states that its payment is guaranteed by you under the Guaranty [promissory_note_excerpt.pdf p.1]. After the Borrower's default and the sale of the collateral, a deficiency remains. The Bank demands payment of that deficiency from you under the Guaranty.

The Guaranty

The Guaranty contains the following key terms [commercial_guaranty.pdf p.1]:

  • Guaranty of payment. You "absolutely and unconditionally" guaranteed "full and prompt payment when due of all present and future indebtedness of Borrower to Lender, including principal, interest, late charges, collection costs and attorney fees." The Guaranty states that it is "a guaranty of payment and not of collection" and that the Bank "need not first pursue Borrower or any collateral" (¶ 1).
  • Amount. "This guaranty is unlimited in amount" (¶ 2).
  • Waivers. You waived notice of acceptance, presentment, demand, protest and notice of default, and any defense based on impairment of collateral or any extension or modification of the indebtedness (¶ 3).
  • Notices. Notices to you are to be sent to 57 Orchard Hill Lane, Linden Ford, Iowa, by certified mail or overnight courier (¶ 4). This letter is sent in that manner.
  • Attorney fees. You agreed to pay the Bank's reasonable attorney fees and costs of enforcing the Guaranty (¶ 5).
  • Governing law. The Guaranty is governed by Iowa law (¶ 6).

[VERIFY: whether the guaranty is unconditional or limited, and what notice it requires] [VERIFY: Iowa rule on guarantor defenses and waivers]

The Default

The Borrower made six monthly payments of $3,671.38 each, from May 7, 2025 through October 7, 2025, totaling $22,028.28 [loan_payment_history.pdf p.1]. The payments due November 7, 2025, December 7, 2025 and January 7, 2026 were not received [loan_payment_history.pdf p.1]. The Bank assessed late charges of $183.57 on each of November 17, 2025, December 17, 2025 and January 17, 2026 [loan_payment_history.pdf p.1]. The Note provides for a late charge of 5% of any payment not received by the 17th of the month [promissory_note_excerpt.pdf p.1].

The events that followed, in date order:

  • January 22, 2026. The Bank issued a Notice of Default and Acceleration to the Borrower, with a copy to you, declaring the entire unpaid balance immediately due [default_notices.pdf p.1; loan_payment_history.pdf p.1]. The unpaid principal at acceleration was $163,214.90, and accrued interest to that date was $3,318.42 [loan_payment_history.pdf p.1]. Certified mail receipts show that both the Borrower's copy and your copy were delivered on January 26, 2026, each signed "N. Kessling" [default_notices.pdf p.1].
  • February 1, 2026. You wrote to the Bank's loan officer that the bakery had closed, that the Bank could pick up the ovens, and that you could not pay anything more at that time [default_notices.pdf p.1].
  • February 3, 2026. The Borrower surrendered the equipment collateral [loan_payment_history.pdf p.1].
  • February 12, 2026. The Bank mailed notice of sale to the Borrower and to you [loan_payment_history.pdf p.1].
  • March 5, 2026. Hawkeye Plains Auction Co. sold the equipment at public auction for gross proceeds of $94,500.00, less an auction commission and transport charge of $9,450.00, for net proceeds of $85,050.00 [loan_payment_history.pdf p.1].
  • March 9, 2026. The Bank applied the net proceeds of $85,050.00 to the indebtedness [loan_payment_history.pdf p.1].
  • March 12, 2026. The Bank wrote to you that a deficiency remains and asked you to contact it to arrange payment [default_notices.pdf p.1]. As of March 18, 2026, the Bank had received no response [default_notices.pdf p.1].

The Security Agreement provides that the Borrower remains liable for any deficiency after the collateral is sold [promissory_note_excerpt.pdf p.1]. The Guaranty makes you liable for that indebtedness.

[VERIFY: Iowa rule on notice of disposition and commercially reasonable sale of collateral as it affects a deficiency claim against a guarantor]

Amount Owed

The Bank's deficiency statement as of March 18, 2026 shows the following [loan_payment_history.pdf p.1]. No cap applies, because the Guaranty is unlimited in amount [commercial_guaranty.pdf p.1].

ItemDateAmountSource
Unpaid principal after application of net auction proceedsAs of March 18, 2026$78,164.90[loan_payment_history.pdf p.1]
Accrued interest (default rate)Through March 18, 2026$4,127.66[loan_payment_history.pdf p.1]
Late charges (three at $183.57)November 17, 2025; December 17, 2025; January 17, 2026$550.71[loan_payment_history.pdf p.1]
Attorney fees incurred to dateAs of March 18, 2026$2,850.00[loan_payment_history.pdf p.1]
Total (as read from the deficiency statement)As of March 18, 2026$85,693.27[loan_payment_history.pdf p.1]

Under the Note, interest on the unpaid principal accrues at 12.25% per year upon default [promissory_note_excerpt.pdf p.1]. Default interest continues to accrue on the unpaid principal from March 19, 2026 [loan_payment_history.pdf p.1]. The Bank's attorney fees and collection costs also continue to accrue under the Guaranty (¶¶ 1, 5) [commercial_guaranty.pdf p.1]. The amount below reflects the Bank's updated balance, including [ADD: per diem default interest amount and updated attorney fees to date of letter].

Demand

The Bank seeks the full deficiency balance, with interest, late charges and attorney fees, under the Guaranty [firm notes]. On the Bank's behalf, we demand that you pay [ADD: demand amount] by [ADD: response deadline], using [ADD: payment instructions].

If payment is not received by that date, the Bank may pursue all of its available remedies against you as Guarantor and against the Borrower, without first pursuing either of you or any other source of recovery [commercial_guaranty.pdf p.1]. Those remedies may include legal action to recover the balance, together with additional interest, attorney fees and costs as provided in the Guaranty and the Note.

This letter is not a complete statement of the facts or of the Bank's rights. The Bank reserves all rights and remedies under the Guaranty, the Note, the Security Agreement and applicable law, and nothing in this letter waives any of them. Please direct all communications about this matter to me at the contact information above.

Sincerely,

Kristin L. Thorsen
Thorsen Gable PC

cc: Harvest Table Bakery LLC, 1218 Walnut Bluff Street, Linden Ford, Iowa [ADD: ZIP]